RSS

How Long Does It Take to Build a House in Edmonton?

Short answer: Building a new production home in Edmonton usually takes about 7 to 12 months from signing the purchase agreement to getting your keys, depending on the builder, the home and the season. A fully custom home often takes a year or longer, plus design time before construction starts. If you need to move sooner, a quick possession home that's already built or nearly finished can close in roughly 30 to 60 days.

By Jay Lewis, REALTOR® | RE/MAX Excellence · Updated September 28, 2026

This article is part of my Edmonton New Construction Buyer’s Guide.

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty, including what to confirm about possession dates before you sign.

I've worked in new construction for more than 25 years, on the trades side (framing new homes, renovations and full contract builds around Edmonton) and the sales side. I've seen schedules from the job site side, so I know where the time really goes and which delays are normal. Here's how long each stage usually takes, what can push your possession date, and how to plan around it.

How long does each type of new home take to build in Edmonton?

  • Quick possession (already built or nearly finished): about 30 to 60 days, mostly the time for financing, your lawyer and the walkthrough.

  • Under construction when you buy: anywhere from a few weeks to several months, depending on how far along it is. Your selection options shrink the further along it is.

  • Production home on a lot that hasn't started: about 7 to 12 months from signing to keys. One Edmonton builder describes its rule of thumb as nine to twelve months.

  • Custom home: often a year or longer for construction, plus several months of design, drawings and permits before work starts.

These are typical ranges, not promises. Your purchase agreement, not the show home conversation, sets the possession date and how it can change.

What happens during the build, and how long does each stage take?

Every builder's schedule is a bit different, but one Edmonton builder publishes a typical timeline that matches what I've seen on site. Counting back from possession day:

  • Pre-construction (about 7 months before possession): purchase agreement, design-centre selections, final drawings and permits.

  • Foundation (about 5 months before): excavation, footings, basement walls, backfill.

  • Framing (about 4 months before): walls, floors, roof trusses and sheathing, windows and exterior doors. The house gets its shape quickly here.

  • Rough-ins and insulation (about 3 months before): plumbing, electrical and heating rough-ins, then insulation and vapour barrier.

  • Drywall, texture and paint (about 2 months before): followed by cabinets, flooring, fixtures and finishing.

  • Final clean and walkthrough (about 3 weeks before): final inspections, cleaning and your pre-possession walkthrough.

Inside a new home before drywall, showing wood stud walls, insulation, wiring and plumbing rough-ins

Illustrative image.

The stage I pay closest attention to for buyers is before drywall. Once the walls are closed, framing, insulation and rough-ins are hidden. If you want an independent inspection by a licensed home inspector, that's the best time to arrange it.

How long do building permits take in Edmonton?

For most production homes, the builder handles permits as part of pre-construction, so you won't deal with them directly. The City of Edmonton publishes its current development and building permit processing times, and they change through the year. On a custom build, permits and drawings can add weeks to the start of construction, so ask your builder to include them in the schedule they give you.

What can delay a new build in Edmonton?

  • Weather: excavation, concrete and exterior work are slower in deep cold, and spring thaw can make lots muddy. A home started in late fall may take longer than one started in spring.

  • Selections running late: most builders set deadlines for design-centre choices. Late or changed selections can push the schedule.

  • Materials and trades: supply problems or trade shortages in a busy season can add weeks.

  • Inspections and utilities: each stage needs inspections, and services such as power and gas have to be connected before possession.

  • Community readiness: in a brand-new phase, roads, utilities and grading around your lot need to be ready too.

Construction prices and schedules change often with market conditions and world events, so treat any timeline as an estimate until it's in writing.

Is the possession date in a builder contract guaranteed?

Not always. Many builder contracts give an estimated possession date and allow the builder to extend it for reasons listed in the agreement, with a notice period. Before you sign, check:

  • Whether the date is firm or estimated

  • How much notice the builder must give if it changes

  • Whether there's a maximum extension

  • What happens to your deposit if the delay is long

Have an Alberta real estate lawyer review the agreement before it becomes firm. My Alberta builder contract checklist covers what to look for.

How do I plan my move around a new build timeline?

  • Selling your current home: avoid locking in a firm sale date until your builder's possession date is confirmed. A flexible possession on your sale, or a short overlap, can save you from paying for storage and a hotel.

  • Renting: check your lease notice period and whether you can go month to month near the end.

  • Mortgage rate hold: a long build can outlast a standard rate hold. Ask your lender about completion mortgages and how long they can hold a rate.

  • GST rebate: timing rules apply to the new First-Time Home Buyers' GST rebate. See my 2026 Alberta new-home GST rebate guide.

  • Need to move sooner? Ask about quick possession homes. Builders in many communities, including those in my Spruce Grove and Sherwood Park guides, regularly have completed or nearly completed homes.

What are the steps to buying a new build, in order?

  1. Get pre-approved and set an all-in budget, including GST, upgrades and closing costs.

  2. Text your REALTOR® before your first show home visit. Many builders have registration policies, and some won't recognize an agent you bring in later.

  3. Visit show homes and compare builders on their included specifications, not the show home finishes.

  4. Choose the lot: orientation, grading, lot type and what's planned next door.

  5. Review the purchase agreement with your lawyer before it becomes firm.

  6. Make your design-centre selections before the builder's deadlines.

  7. Construction: stay in touch with your builder and consider an inspection before drywall.

  8. Pre-possession walkthrough: document every deficiency in writing.

  9. Possession: your lawyer completes the purchase and you get your keys. Your Alberta new home warranty starts.

More detail: show home sales rep vs. buyer's agent · which upgrades are worth it.

Get my free New-Construction Buyer Checklist

Want every step above, plus what to check in the contract and during the build, on two printable pages? My free checklist takes you from your first show home visit to your one-year warranty.

Get the free checklist →

Frequently asked questions

How long does it take to build a house in Edmonton?

Usually about 7 to 12 months from signing to possession for a production home, and a year or longer for a custom home. Quick possession homes can close in about 30 to 60 days.

Can I build a house faster in summer?

Often, yes. Excavation, concrete and exterior work go more smoothly in warm weather. A home started in late fall is more likely to see weather delays.

What is a quick possession home?

A new home the builder has already built or nearly finished, often called a spec home. Selections are mostly made, but you can move in much sooner.

Can a builder change my possession date?

Many builder contracts allow it for reasons listed in the agreement, with notice. Check the possession and extension terms with your lawyer before you sign.

When should I get an inspection on a new build?

The most useful time is before drywall, when framing, insulation and rough-ins are still visible, plus before your pre-possession walkthrough.

Planning a new build in the Edmonton area?

If you're working out timing for a new home in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, text me first at 780-220-8449, or book a 20-minute call. I'll help you compare quick possessions with homes still to be built, and plan the timing around your current home. I also list homes for some builders; if you're interested in one of my listings, I'll tell you up front and explain how representation works. I'm not a home inspector, engineer or lawyer, and I'll tell you when you need one.

Jay Lewis | REALTOR® | RE/MAX Excellence

Sources:Sterling Homes Edmonton: How long does it take to build a new home? · City of Edmonton: permit processing times · Government of Alberta: new home warranty

This article is general information, not legal or mortgage advice. Timelines vary by builder, home and season; confirm dates in your purchase agreement.

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.
Read

Which New Home Upgrades Are Worth It? A Construction-Informed Guide for Edmonton Buyers

Short answer: Prioritize upgrades that improve how you use the home, provide a measurable benefit over the builder’s included specifications, and would be difficult or disruptive to add later. Layout changes, useful rough-ins and well-designed energy-performance improvements deserve early attention. Decorative fixtures and finishes can wait when the standard choices already meet your needs.

This article is part of my Edmonton New Construction Buyer’s Guide.

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty, including what to confirm about upgrades and selections.

Correct installation, required drainage, appropriate mechanical design and code compliance are baseline expectations. Buyers should not have to select an upgrade package to obtain properly completed work.

If you are choosing builder options in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, begin with the included specifications and your total budget. An upgrade is worth considering because of the difference it makes to your home, not simply because it appears in a premium package.

By Jay Lewis, REALTOR® | RE/MAX Excellence
Reviewed September 21, 2026


How do I decide whether a builder upgrade is worth the price?

My approach is to evaluate each option against four questions:

  1. What is already included? Identify the standard product, specification or layout before paying to change it.

  2. What does the upgrade improve? Look for a specific benefit in comfort, function, durability or appearance.

  3. What would changing it later involve? Consider demolition, access, replacement work and disruption as well as the product price.

  4. Will you use the benefit? A feature can be valuable to one household and unnecessary for another.

A higher purchase price does not guarantee lower operating costs or a matching increase in resale value. Decide whether you are paying for everyday enjoyment, future flexibility or a measurable performance improvement.

Upgrade categoryWhen it deserves a close lookWhat to confirm
Layout and structural optionsThe standard plan does not fit a lasting needApproved design, total price and selection deadline
Electrical and plumbing rough-insYou have a realistic future useLocations, capacity, included work and later completion costs
Insulation and air sealingThe package improves the included assemblyWritten specifications, performance targets and testing
WindowsThe proposed product offers useful performance improvementsWhole-window ratings, orientation and installation details
Heating, cooling and ventilationAdded features address a defined comfort needDesign basis, equipment, controls and commissioning
Cabinets and flooringThe standard option falls short in function or durabilityConstruction, material limits, layout and replacement implications
Decorative fixtures and finishesYou value the appearance and have room in the budgetUpgrade premium and practical alternatives

This is a decision framework, not a ranking of guaranteed financial returns.


What should already be included before I pay for upgrades?

Proper construction is the starting point. A home must meet the requirements applicable to its construction. Alberta publishes its building codes and standards, which should be distinguished from optional features or higher performance targets.

That distinction matters when discussing window installation, bathroom water protection, drainage and mechanical design. Ask the builder to explain what the base specification provides and exactly how a proposed upgrade differs.

For example, a higher-performance window is a product choice. Correctly installing the selected window is part of completing the work properly. Similarly, a custom shower is an option; the required water-management details for that shower are part of its construction.

Warranty coverage is a separate consideration. Review the applicable warranty documents and reporting procedures. Alberta’s new-home warranty overview explains minimum coverage and relevant conditions. An upgrade description should not substitute for a clear specification or warranty information.


Before You Visit or Register With a Builder

If you want your own representation, text me at 780-220-8449 before visiting a show home, registering online or beginning direct negotiations. Builder cooperation and registration policies vary, and some require your REALTOR® to be identified at the first visit.


Which upgrades should I decide on before construction starts?

Layout and Structural Options

Prioritize changes that solve a lasting problem. A garage configuration, doorway location, window opening or room layout may be difficult to change once the home is built. If the standard plan does not accommodate your vehicle, furniture, mobility needs or intended use, investigate that before choosing finish packages.

Ask which changes the builder offers, what design or engineering work they require, and when decisions become final. Approval requirements and feasibility depend on the property and proposed change. Adding square footage or complexity should be a deliberate budget decision.

Wood-framed interior of a new home under construction with electrical wiring and boxes installed

Electrical, Data and Plumbing Rough-Ins

Plan around a realistic future use. Potential items include a conduit route for future wiring, outlets positioned for your furniture, an EV-charging plan, or plumbing rough-ins aligned with a future basement layout.

“EV-ready” and “basement rough-in” can describe different scopes. Ask whether the price covers a pathway, wiring, a circuit, equipment, or only some of those components. Have the relevant trade assess capacity and suitability rather than assuming spare panel spaces establish available electrical capacity.

Before committing, request a marked plan and written scope. A rough-in has limited value if its location does not suit the room you eventually intend to build.

Insulation and Air Sealing

Look for an improvement you can define. The building envelope, the assemblies separating indoors from outdoors, works as a system. Ask which parts of that system change, how the improvement will be assessed, and how ventilation is addressed alongside airtightness.

A blower-door test measures air leakage; it does not measure insulation quality by itself. Natural Resources Canada’s EnerGuide glossary explains the test and related terms.

Request the included and proposed insulation specifications, any airtightness target and the testing process. Where energy savings are part of the sales claim, ask for a home-specific assessment and its assumptions. “Extra insulation” alone is not enough information to establish value.

Window Performance

Compare the actual window, rather than the package name. Natural Resources Canada identifies U-factor as a measure of heat loss through a window assembly; a lower value indicates less heat loss. Solar heat gain also matters, with suitability affected by orientation, shading and the home’s design. Source: NRCan’s guide to windows and exterior doors.

Ask for the exact standard and upgraded products and their whole-window ratings. If the standard specification already performs well, the next step up needs to justify its price. More glazing or a premium appearance is not automatically a comfort improvement.

Heating, Cooling and Ventilation

Correct sizing belongs in the base design. An upgrade discussion should focus on what additional equipment or features achieve, rather than treating a larger system as inherently better.

Ask how the design accounts for the selected layout, windows and insulation. NRCan’s heat-pump guidance specifically emphasizes accounting for building-envelope improvements when assessing heating needs to avoid oversizing.

For an air-conditioning package, request the equipment details, installation scope and explanation of sizing. For comfort concerns in particular rooms, ask the mechanical designer how distribution and controls address those rooms. A thermostat upgrade alone does not establish that a room-level comfort problem has been solved.


How should I compare flooring, cabinet and garage options?

Flooring for Entries and Busy Rooms

Choose for the household using it. Wet footwear, pets, children and cleaning habits belong in the decision. Compare the actual product’s maintenance instructions, moisture limitations, scratch resistance and installation requirements.

Hard flooring is not one uniform category: tile, wood, laminate and vinyl have different characteristics. Carpet can be a practical choice where warmth and comfort are priorities. Avoid paying for a premium label without understanding what changes in the product.

Finished new-home kitchen with a wood island, quartz countertops and pantry storage

Kitchen Cabinets and Storage

Treat layout and cabinet construction as lasting decisions. Handles and pulls can be relatively straightforward to change, but cabinet boxes, layout, countertop relationships and appliance openings are more involved. Refacing is not always practical or inexpensive.

Evaluate useful drawers, pantry access, clearances and storage before choosing a decorative door profile. You may reasonably prioritize a kitchen feature you will use every day, even if it does not improve energy performance.

For countertops, compare the actual materials, care requirements and price difference. Neither granite nor quartz is automatically the better purchase for every household.

Garage Doors and Future Heating

Assess the garage as a whole. An insulated door deserves a different evaluation in a garage intended to be heated than in one used only for parking. Ask about the door assembly, seals, surrounding construction and the intended heating plan rather than relying on one insulation number.

If you are considering a future heater, request a written explanation of what any preparation includes. Have the relevant professionals confirm the installation requirements. Do not assume that selecting an insulated door makes the entire garage ready for heating.


Which builder upgrades can wait until after possession?

Decorative lighting. If the wiring, switching, support and locations already suit the plan, the fixture style can be a later decision. Confirm any special requirements before postponing a selection.

Premium paint and feature treatments. These can offer personal enjoyment, but they do not need to take priority over a layout problem or a useful rough-in. Consider how much repainting or finish work you are actually willing to arrange after possession.

Hardware and accessories. Compare the builder’s upgrade charge with the complete cost of an alternative, including installation and any standard items you would discard.

Deferring an upgrade does not automatically save money. Paying the builder once can be preferable to paying for a standard product and replacing it shortly afterward. Compare both paths before deciding.


What should I bring to a builder options meeting?

Start with the floor plan, included specifications and a firm allowance for optional changes. Keep a separate allowance for work and purchases needed after possession.

For each option, record:

  • The standard item and proposed replacement

  • The complete price, including applicable taxes and related work

  • The product, model, dimensions or performance specification

  • The selection deadline and later change charges

  • Who completes the work and what remains excluded

Finish by reviewing the combined total. Several individually affordable selections can add up to more than the budget allows. Confirm the selections in the builder’s written change process, and direct contract questions to your lawyer before becoming firm.

If you want a second set of eyes on a builder’s options package before committing to selections, call or text me at 780-220-8449. Have the floor plan, included specifications and upgrade pricing ready so we can compare what each option adds to your home and budget.


My Take as a Local REALTOR®

After more than 25 years in new construction, on the trades side through Konstruct (framing, renovations and full contract builds) and the sales side, I look at an options sheet in terms of what the change accomplishes and what replacing it later would involve.

I would rather see a buyer make a few deliberate decisions than purchase a package without understanding its contents. A well-positioned rough-in may support a future plan. A cabinet change may make daily life easier. A window package may improve performance. Each needs a reason that fits the home and the buyer.

My role is to help compare the specifications, costs and practical trade-offs. Technical design, code interpretation and inspections remain the responsibility of the appropriate professionals.

If you are still deciding between a new build and an existing home, my Edmonton new-construction versus resale guide explains how to compare the overall purchase.


Get the New-Construction Buyer Checklist

Choosing upgrades for a new home in Edmonton or the surrounding area? Get my free new-construction buyer checklist, and text me for help comparing your builder’s included specifications, upgrade options and total budget.

If you are still deciding between new construction and resale, I can also help you compare what your budget can buy in both markets.

Call or text me: 780-220-8449
Email: jay@jaysells.ca
Website: jaysells.ca

Your search. Your timeline. No pressure.


Related guides: New construction cost per square foot in Edmonton · Alberta builder contract checklist · Do I need a REALTOR® to buy a new build?

Frequently Asked Questions

Which upgrades add the most resale value?

There is no universal ranking that guarantees a return. Buyer preferences, location, property type and market conditions affect value. Choose upgrades for their documented benefits and your expected use; do not assume the resale price will increase by the amount spent.

Should I pay for triple-pane windows?

Compare the builder’s included windows with the proposed upgrade first. Ask for whole-window performance ratings, the price difference and how the selection suits the home’s orientation. Pane count alone does not establish whether the additional cost is worthwhile.

Is it cheaper to install air conditioning after possession?

It depends on the builder’s price, the proposed equipment and the later installation requirements. Obtain comparable written scopes and have sizing confirmed. Include any preparation already offered by the builder when comparing costs.

Should I finish the basement with the builder or later?

Compare the complete scope, cost, timing and disruption of each option. If you plan to wait, settle the intended layout before selecting rough-ins. Preparation for a future basement does not necessarily include everything required to complete it.

Can I negotiate an upgrade package?

Ask what flexibility the builder offers on the specific home and selections. Evaluate a credit against actual option prices and the items you want. A large promotional allowance has less personal value if it applies primarily to features you would not otherwise purchase.


Sources and Important Information

The sources support the technical background; the upgrade priorities and comparison approach are my professional perspective. This article provides general education, not a property-specific design, inspection or guarantee of savings. Confirm specifications, warranties, inclusions and technical requirements with the builder and qualified professionals.

If you're comparing your options or planning a move in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, I can help you understand how the details fit into the bigger picture.

Call or text me at 780-220-8449

Jay Lewis | REALTOR® | RE/MAX Excellence

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.

Read

Is Edmonton a Buyer's Market? What 18,544 Homes Under Construction Mean for You

Short answer: Edmonton's resale market softened in August, sales down, inventory up, prices flat to slightly lower, while the city simultaneously kept 18,544 homes moving through construction, one of the strongest population-adjusted building rates of any major Canadian market. Those two facts are usually reported separately. Looked at together, they point toward more choice and more negotiating room for buyers over the months ahead, whether they're shopping resale or new construction.

By Jay Lewis, REALTOR® | RE/MAX Excellence · Updated October 21, 2026

This article is part of my Edmonton New Construction Buyer’s Guide.

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty.

Edmonton Real Estate Market Snapshot  September 2026

The latest complete statistics available when this article was published cover August 2026, for Greater Edmonton (Edmonton and several surrounding municipalities), alongside CMHC's newest construction data reported September 16, 2026.

Sources: REALTORS® Association of Edmonton, August 2026 statistics; CMHC, Fall 2026 Housing Supply Report and August 2026 construction data; Bank of Canada, September 2, 2026 rate decision.

For current advertised mortgage-rate examples, see MortgagesForLess.ca's Alberta mortgage rates. For Bank of Canada announcements and local context, see Edmonton Home Team's Bank of Canada updates. Actual mortgage rates vary by lender, down payment, mortgage-insurance status, amortization, property and borrower qualifications.

What the Board's Own Numbers Show

  • Sales: 2,143 residential sales in August, down 15.4% from July and down 9.8% from a year earlier

  • New listings: 3,769, down 8.1% month over month but still up 3.3% year over year

  • Inventory: 15.1% higher than August 2025

  • Average selling price: $469,602, down 1.1% from July but up 1.8% year over year

  • MLS® HPI composite benchmark price: $426,900, down 0.6% from July and down 0.6% from August 2025

  • Sales-to-new-listings ratio: approximately 56.9% (2,143 sales ÷ 3,769 new listings)

The REALTORS® Association of Edmonton didn't officially call this a buyer's market. But its own language is worth paying attention to, the Association said there are indicators that "a shift in the wider market is taking place," and warned that ample supply without enough demand could put downward pressure on prices beyond normal seasonal patterns.

That sales-to-new-listings ratio of 56.9% still sits inside the standard "balanced" range on paper. What matters more is the direction: sales falling, inventory building, the benchmark price softening, and the board itself flagging what could happen next if demand doesn't keep pace.

Meanwhile, Edmonton Keeps Building

CMHC's newest data shows Edmonton had 18,544 homes under construction in August 2026, up from 18,289 in July. The pipeline has grown every month since spring:

  • May: 17,440

  • June: 17,878

  • July: 18,289

  • August: 18,544

The growth rate is slowing, though:

  • May → June: +2.5%

  • June → July: +2.3%

  • July → August: +1.4%

At the same time, approved units waiting to start construction have moved from 5,503 in June to 5,316 in July and 5,262 in August. That doesn't mean Edmonton builders have stopped building, they haven't. It means a very large amount of housing is still moving through the pipeline, while there are early signs worth watching around what comes next.

Edmonton Is Still Building at One of the Strongest Rates Among Major Canadian Markets

A raw number like 18,544 doesn't tell you whether that's actually a lot relative to the size of the city. CMHC's Fall 2026 Housing Supply Report answers that by comparing housing starts per 10,000 residents across major Canadian markets for the first half of 2026:

  • Calgary: 61

  • Edmonton: 51

  • Vancouver: 41

  • Ottawa: 37

  • Montréal: 30

  • Toronto: 19

Bar chart of housing starts per 10,000 people in the first half of 2026: Calgary 61, Edmonton 51, Vancouver 41, Ottawa 37, Montreal 30, Toronto 19 (source: CMHC)

Among the six markets CMHC compared, only Calgary built more per capita. Edmonton's rate is down about 20% from the unusually high pace set in 2025, but CMHC's own report notes construction here "remains above historical averages", meaning this is a slowdown from a very high level, not from a low one. A significant amount of housing is already committed and will keep moving toward completion regardless of what resale demand does in the short term.

Why Completions Bounce Around So Much

July completions jumped to 1,729 units. In August they dropped 11.4% to 1,532. I wouldn't read too much into either month by itself.

Multi-family construction makes completion numbers naturally lumpy. If a large apartment project finishes, hundreds of units can move into the completed category at essentially the same time, July's 1,729 completions included 908 apartment units, more than half the total, almost certainly reflecting one or two larger buildings wrapping up at once. The next month can then show a substantial decline without anything fundamentally changing in the market. That's why the overall construction pipeline is more informative than whether completions happen to be up or down in any single month.

What This Means If You're Buying

  • You likely have more room to compare homes, neighbourhoods, builders and specifications than you did a year ago, rather than feeling pressure to jump at the first listing that fits.

  • New construction and resale increasingly compete for the same buyers, a family looking at a detached home might be comparing a five-year-old resale property with a quick-possession home from a builder.

  • If you're considering new construction, look at the all-in price, not just the advertised base price. Confirm whether GST is included and whether the builder's price assumes an available rebate. Qualifying first-time buyers may be eligible for up to $50,000 through the [First-Time Home Buyers’ GST Rebate]. Builder incentives, such as appliances, air conditioning, landscaping, upgrades or possession terms, should also be valued based on what they are actually worth to you.

    Financing conditions matter too. Buyers should compare current mortgage rates, but amortization can matter just as much. If your down payment is less than 20%, a 30-year insured mortgage may be available if you're a first-time buyer and/or purchasing a new build. See my 2026 guide to 30-year mortgages in Alberta for the current rules and payment trade-offs.

If you want a second set of eyes on a specific listing or builder offer before you commit, call or text Jay Lewis at 780-220-8449 no pressure, just a sounding board.

What This Means If You're Selling

  • Understanding your competition matters more than it did a year ago, and your competition may not just be another resale home down the street. If you're near an active new community, buyers may be comparing your home against a brand-new property.

  • That comparison isn't purely about price. A resale home may already have landscaping, fencing, a deck, window coverings, appliances or a finished basement; a new home may offer warranty coverage and modern systems. Buyers weigh the whole package.

  • With inventory up 15.1% year over year, accurate pricing from the start matters. Overpricing into a market with this much competing supply typically means a longer time on market and eventual price reductions.

If you're weighing when to list or how to price against nearby new construction, reach out to Jay Lewis at 780-220-8449 or jay@jaysells.ca for a current comparison of your specific street.

What This Means If You're Building or Considering New Construction

  • A growing under-construction count paired with a shrinking not-yet-started pool suggests the next wave of completions will land in a resale market that's already softening, worth factoring into your timing if you have flexibility.

  • If you want a deeper comparison of the two paths, I've written a full guide to new construction vs. resale homes in Edmonton, covering warranty coverage, GST treatment, contract terms and what to watch for with a builder's sales representative.

  • Before you register with or visit a builder's show home, contact Jay Lewis at 780-220-8449 if you want your own representation, builder cooperation and registration policies vary, and some require your REALTOR® to be identified at the first visit.

So, Is Edmonton Becoming a Buyer's Market?

The numbers tell us something more useful than the label. Inventory is higher, sales are lower, the benchmark price has softened slightly, and the REALTORS® Association of Edmonton is openly warning that prices could face additional downward pressure if demand doesn't keep pace with supply. That's a market shifting in the buyer's direction.

But Edmonton isn't experiencing a housing-market collapse. The benchmark price is only 0.6% lower than a year ago, while the average selling price remains 1.8% higher. Both things can be true at once: buyers can be gaining leverage without prices falling dramatically.

What I'm Watching Next

The more interesting question isn't whether we can officially call Edmonton a buyer's market today, it's what happens next. Resale inventory is already elevated and demand has softened, while 18,544 homes remain under construction and Edmonton posts one of the strongest population-adjusted building rates among major Canadian markets. If resale inventory stays elevated while that construction pipeline moves toward completion, buyers could gain additional leverage. If demand strengthens enough to absorb the new supply, the picture could shift again. That's why I'm watching the pipeline, not just this month's sales number.

For buyers right now, the important thing is that you have something valuable: more choice. Use it.

Get the New-Construction Buyer Checklist

Trying to decide between new construction and resale in Edmonton or the surrounding area? Contact Jay Lewis for a new-construction buyer checklist and a side-by-side comparison of what your budget can buy in both markets.

Call or text Jay Lewis: 780-220-8449 Email: jay@jaysells.ca Website: jaysells.ca

Get my free New-Construction Buyer Checklist

Thinking about a new build? My free, printable 2-page checklist covers what to check at every stage, from your first show home visit to your one-year warranty.

Get the free checklist →

Frequently Asked Questions

Is Edmonton a Buyer's Market in 2026?

Edmonton is showing more buyer-friendly conditions, but the market is not uniform across every neighbourhood, property type or price range. In August, inventory was 15.1% higher than a year earlier while residential sales were 9.8% lower. The better takeaway is that many buyers have more choice and negotiating room than they did earlier in the year.

How Many Homes Are Under Construction in Edmonton?

CMHC reported 18,544 homes under construction in the Edmonton CMA in August 2026, up from 18,289 in July.

Is Edmonton Still Building a Lot of Homes Compared With Other Canadian Cities?

Yes. Edmonton recorded approximately 51 housing starts per 10,000 residents in the first half of 2026, placing it among the highest construction rates of the major markets compared in the CMHC report.

Why Are So Many Homes Still Under Construction if the Market Is Slowing?

Construction responds to changing conditions with a delay. Homes and multi-family projects that are already underway continue toward completion even when resale demand begins to soften.

Could More New Construction Push Edmonton Home Prices Lower?

More supply can increase buyer choice and competition, but construction alone does not determine prices. Demand, population growth, interest rates, location, property type and the pace at which inventory is absorbed all matter.

Should I Wait to Buy a Home in Edmonton?

There is no reliable way to identify the exact bottom of a housing market in advance. More inventory can create better selection and negotiating opportunities, but the decision should depend on the specific property, your financing, your timeline and how long you expect to own the home.

Why Did Edmonton Home Completions Drop in August?

Monthly completions can vary significantly, particularly when large multi-family projects finish in batches. One month's decline does not necessarily indicate that construction activity has stopped or materially changed direction.

Sources and Important Information

Thinking About Buying in Edmonton?

If you're comparing your options or planning a move in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, I can help you understand how the details fit into the bigger picture. With more than 25 years in new construction, on the trades and sales sides, I bring a builder’s eye perspective to the buying process.

Call or text Jay Lewis at 780-220-8449

Jay Lewis | REALTOR® | RE/MAX Excellence

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.

This article provides general information only and is not legal, tax, accounting or mortgage advice. Real-estate market statistics, construction data and mortgage rates can change. Confirm information that applies to your specific transaction with the appropriate qualified professional. The August 2026 completions figure for Edmonton is cited as reported by CMHC's September 16 release.

Read

New Construction vs. Resale Homes in Edmonton: Which Is Better in 2026?

Short answer: Neither option is automatically better. New construction offers current building standards, mandatory warranty protection on most qualifying homes, and opportunities to choose finishes or structural options. Resale offers established neighbourhoods, a negotiated possession date, and generally no GST on a typical previously occupied home. The right choice depends on your budget, preferred location, timeline, tolerance for construction uncertainty and the total cost of each property.

By Jay Lewis, REALTOR® | RE/MAX Excellence · Updated October 21, 2026

This article is part of my Edmonton New Construction Buyer’s Guide.

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty. Handy if you're weighing a new build against resale.

If you are buying in Edmonton or the surrounding area in 2026, compare the two options using all-in costs, not only the advertised price.


Edmonton Real Estate Market Snapshot, September 2026

The latest complete statistics available when this article was published cover August 2026. The figures below are for the Greater Edmonton Area (GEA), which includes Edmonton and several surrounding municipalities.

Market indicatorAugust 2026
Average MLS® residential selling price$469,602 (+1.8% year over year)
Median MLS® residential selling price$439,000 (+0.9% year over year)
MLS® HPI composite benchmark price$426,900 (−0.6% year over year)
Single-family HPI benchmark priceApproximately $525,000 (−0.2% year over year)
Residential inventory8,052 properties (+15.1% year over year)
Months of inventory3.8 months
Average days on market for monthly sales41 days, compared with 37 days in August 2025
Residential sales2,143 (−9.8% year over year)
Bank of Canada policy rate2.25%, held September 2, 2026
Advertised five-year fixed mortgage ratesApproximately 4.09% to 4.64%, depending on the mortgage and borrower

Sources: REALTORS® Association of Edmonton, August 2026 statistics and Bank of Canada, September 2, 2026 decision.

For current advertised mortgage-rate examples, see MortgagesForLess.ca’s Alberta mortgage rates. For Bank of Canada announcements and local context, see Edmonton Home Team’s Bank of Canada updates. Actual mortgage rates vary by lender, down payment, mortgage-insurance status, amortization, property and borrower qualifications.

See MortgagesForLess.ca’s Alberta mortgage rates, and the Edmonton Home Team Bank of Canada updates for additional context.


What the 2026 Market Means for Buyers

The August numbers point to a market with more supply and slower sales than one year earlier. Inventory was 15.1% higher, sales were 9.8% lower and properties that sold took an average of 41 days rather than 37.

That does not mean every property is easy to negotiate. Conditions vary by municipality, neighbourhood, price range and property type. Attractive homes that are priced appropriately can still sell quickly, while properties that miss the market may remain available longer.

For buyers, the practical message is straightforward: there may be more opportunity to compare properties and negotiate than there was in a tighter market, but strong listings can still require prompt decisions.

New construction adds another layer of supply that MLS® statistics do not fully capture. As of September 2026, Livabl listed approximately 299 new-home communities, including 181 single-family communities, 2,827 floorplans and units, and 946 quick-possession homes in its Edmonton search area.

Those figures are not directly comparable with MLS® inventory. Livabl’s database includes developments that are planned, under construction or recently completed, along with builder inventory that may or may not be listed on MLS®. The numbers are useful as an indication of the size of the broader new-construction market, not as a count of communities with homes available for immediate purchase. Not every new-construction opportunity is advertised on MLS®. Contact Jay Lewis at  780-220-8449 before registering with or visiting a builder to compare MLS® listings with builder-marketed quick-possession and to-be-built homes that may be available.


Option 1: Buying New Construction

What new construction can offer

A home built to current requirements. A newly permitted home must meet the building requirements applicable to its construction. Newer homes commonly include updated insulation, air-sealing, windows and mechanical systems compared with older homes that have not been upgraded. Actual utility costs still depend on the home’s size, design, systems, weather and occupants’ energy use.

Mandatory warranty protection on most qualifying new homes. Under Alberta’s New Home Buyer Protection Act, most new homes with building permits applied for on or after February 1, 2014 require warranty coverage. The minimum protection is:

  • One year for labour and materials

  • Two years for defects in delivery and distribution systems, including electrical, plumbing, heating, ventilation and air conditioning

  • Five years for the building envelope

  • Ten years for major structural components

There are limited exemptions, including certain authorized owner-built homes. Coverage also has terms, limits and exclusions. Alberta new-home warranty overview.

Opportunities to personalize the home. Depending on when you purchase and what the builder permits, you may be able to choose finishes, cabinetry, flooring, countertops and fixtures. Some builders also offer structural options such as garage changes, additional windows, separate entrances or modified layouts. The options and deadlines vary by builder and stage of construction.

Potential GST relief for eligible buyers. Qualifying first-time buyers may recover up to 100% of the federal GST on a qualifying new home valued at $1 million or less, to a maximum of $50,000. The first-time-buyer rebate is reduced between $1 million and $1.5 million and is unavailable at $1.5 million or more. Eligibility and transaction dates matter.

Read the complete 2026 Alberta new-home GST rebate guide.

What buyers need to watch

The total price, not the base price. A builder’s starting price may not include the lot premium, preferred elevation, upgrades, landscaping, fencing, window coverings, appliances, deck, garage finishing or other items a buyer expects. GST may already be included in the advertised price, and the price may assume that an available rebate is assigned to the builder.

Before comparing a new home with resale, request a written breakdown of:

  • Base price and lot premium

  • Included specifications

  • Selected upgrades

  • GST and assumed rebates

  • Deposits and payment schedule

  • Closing adjustments

  • Items the buyer must complete after possession

Construction and possession timing. A home built from the ground up normally requires a much longer timeline than a typical resale purchase. The builder’s estimated possession date can change because of permitting, materials, labour, weather, inspections and other contract terms. A quick-possession home may be available considerably sooner, but the buyer has less opportunity to change the design and finishes.

Location and developing amenities. New greenfield construction exists around Edmonton’s outer south, southwest, west, southeast, northeast and north edges, as well as in surrounding municipalities. Choices vary by home type and builder.

New communities can involve ongoing construction, changing traffic patterns and amenities that are not complete. School sites and commercial areas shown on a concept plan do not guarantee a specific completion date. Buyers should verify the schools, transportation and services available today and recognize that school attendance boundaries can change.

The contract. Builder agreements are commonly written by the builder and can differ substantially from a standard resale contract. Buyers should understand deposit terms, financing conditions, construction changes, measurements, possession delays, closing adjustments, inspection rights and warranty procedures. Independent legal advice should be obtained before the agreement becomes firm.


The Builder’s Sales Representative and Your Representation

The builder’s sales representative works for the builder. Their role is not the same as having a real-estate professional representing the buyer’s interests.

Builder policies concerning REALTOR® cooperation and registration vary. Some require the buyer’s REALTOR® to accompany the buyer or be identified at the first visit or registration. If you want your own representation, contact your REALTOR® before visiting a show home, registering online or beginning direct negotiations with a builder.

Buyer representation can help with more than finding the development. It can include comparing lots, reviewing specifications and allowances, identifying omitted items, evaluating upgrade costs, understanding the builder’s paperwork, planning inspections, attending walkthroughs and documenting deficiencies. Legal questions and contract interpretation should still be handled by the buyer’s lawyer.


Inspections, Walkthroughs and Deficiency Lists on a New Home

A warranty is valuable, but it is not a substitute for careful inspections and documentation.

Depending on the builder, contract and stage of construction, a buyer may consider:

  • Reviewing plans, specifications and change orders during construction

  • Asking whether independent progress inspections are permitted

  • Completing a detailed pre-possession walkthrough

  • Recording incomplete or deficient work in writing

  • Learning the builder and warranty provider’s reporting deadlines

  • Considering an independent home inspection before possession or during the first warranty year

Warranty programs address eligible defects after the applicable requirements are met. Identifying and documenting concerns early can make them easier to address.

Jay Lewis reviewing construction details in a new Edmonton home

Illustrative image of Jay Lewis reviewing a new home’s construction details.

This is an area where my background matters. I bring more than 25 years in new construction, on the trades and sales sides, including framing, renovations, full contract builds, and helping clients buy and sell new-construction homes. I do not present myself as the builder or replace the work of inspectors, engineers or lawyers. My role is to help buyers ask better questions, compare what is included and recognize details that may deserve closer review.


Option 2: Buying a Resale Home

Resale homes in an established Edmonton neighbourhood

An established Edmonton-area streetscape, shown for illustration.

What resale can offer

Established locations. Resale gives buyers access to mature neighbourhoods, existing schools and services, established transit routes, completed landscaping and a wider range of locations. Buyers should still verify current school attendance areas and future plans rather than assume they will never change.

Generally no GST on a typical previously occupied home. Most ordinary sales of used residential homes are exempt from GST. Exceptions can arise, including certain substantially renovated properties or unusual transactions, so buyers should obtain tax and legal advice when the property’s history is unclear.

A negotiated possession date. Unlike a home that is still being constructed, a completed resale property allows the buyer and seller to negotiate a specific possession date in the purchase contract. The date is not solely the buyer’s choice, it must be accepted by both parties.

The ability to assess what already exists. Buyers can see the finished home, lot, street and surrounding development. A home inspection can help identify visible concerns before conditions are removed, although no inspection can guarantee that every concealed or future issue will be found.

What buyers need to watch

Age and condition. Roofing, windows, drainage, foundation, plumbing, electrical systems, heating equipment and previous renovations can all affect future costs. The home’s age alone does not determine its condition; maintenance and the quality of previous work matter.

Renovation costs. A lower resale purchase price may not remain lower after replacing flooring, kitchens, bathrooms, windows or mechanical systems. Compare the realistic cost of making the property work for you, not only its purchase price.

Remaining new-home warranty. A newer resale home may still have warranty protection. Alberta’s new-home warranty attaches to the home, not only to the original owner, and remains in effect after a resale until the applicable coverage expires. Buyers can search Alberta’s property registry and review the warranty documents to determine what remains.


The GST Difference: Compare the Contract, Not the Headline Price

New homes in Alberta are generally subject to 5% federal GST. A qualifying first-time buyer may receive substantial relief under the First-Time Home Buyers’ GST/HST Rebate, while another buyer may pay more GST on the same home.

That does not mean every eligible buyer receives money back after closing. The builder may credit an assumed rebate in the contract and require the buyer to assign the rebate to the builder. If the buyer does not qualify, the contract may require the buyer to pay the difference.

When comparing new construction with resale, determine:

  1. Whether the new-home price includes GST

  2. Whether an assumed rebate has already been deducted

  3. Which rebate the buyer may qualify for

  4. Who will apply for or receive the rebate

  5. What the buyer owes if the CRA denies the claim

Confirm the calculation with the builder, CRA, an accountant and your real-estate lawyer before relying on the rebate in your budget.


New Construction vs. Resale: Side-by-Side Comparison

ConsiderationNew constructionResale
GSTGenerally subject to 5% GST; rebates may be availableMost typical used-home sales are GST-exempt
WarrantyMandatory 1/2/5/10-year minimum coverage on most qualifying new homesA newer resale may retain the balance of its original new-home warranty
PossessionDepends on construction stage and contract; estimates may changeA specific date is negotiated between buyer and seller
CustomizationOften available when purchased early enoughExisting layout and finishes; renovations are completed after purchase
LocationCommon in developing areas, infill projects and surrounding municipalitiesBroad choice across established and developing neighbourhoods
Energy performanceBuilt to requirements applying at the time of constructionVaries by age, construction, upgrades and maintenance
Inspection needsWalkthroughs and independent inspections remain valuableA pre-purchase inspection is an important risk-management tool
Price comparisonMust include lot, upgrades, GST treatment and unfinished itemsMust include anticipated repairs, replacements and renovations
Neighbourhood certaintyFuture amenities and construction timelines may changeExisting surroundings are visible, although future change remains possible

Who Is Usually Better Suited to Each Option?

New construction may make more sense when you:

  • Have flexibility around the possession timeline

  • Value warranty protection and newer systems

  • Want to choose finishes or available design options

  • Are comfortable living in a developing area or buying infill

  • Are prepared to compare the complete specifications and all-in price

  • May qualify for the First-Time Home Buyers’ GST/HST Rebate

Resale may make more sense when you:

  • Need to negotiate a specific possession date

  • Want an established neighbourhood or particular location

  • Prefer to evaluate the completed home and surroundings

  • Want to avoid the uncertainty of a construction schedule

  • Find a home whose condition and renovation needs fit your budget

Many buyers will not know which option is better until they view both. Comparing resale properties in the locations you prefer with new homes at a similar all-in budget is often the clearest way to decide.


What Sellers Should Know in 2026

New construction is also part of the competition for resale sellers, particularly in areas near active developments.

A resale home may compete well by offering an established yard, completed window coverings, appliances, fencing, a deck, a finished basement, air conditioning or a faster and more dependable possession timeline. A new home may compete through warranty protection, modern design, builder financing promotions or buyer choice.

When pricing a resale property, sellers should compare more than another home’s advertised base price. The relevant comparison is the buyer’s likely finished, all-in cost and the value of what is already included in the resale property.

With Greater Edmonton inventory 15.1% higher than a year earlier, accurate pricing and clear presentation matter. That does not mean every seller must discount heavily; it means buyers have more alternatives and are more likely to compare value carefully.


My Take as a Local REALTOR®

New construction and resale are different products, and I do not believe buyers should decide between them based on assumptions.

With more than 25 years in new construction, on the trades and sales sides, including framing, renovations, full contract builds, and helping clients buy and sell new-construction homes, I look beyond the show-home finishes. The lot, specifications, allowances, upgrade pricing, contract terms, walkthrough process and items excluded from the price can matter as much as the floor plan.

Resale deserves the same practical analysis. An older home can be well built and carefully maintained, while a newer home can still require close inspection. The goal is not to declare every new home better than every resale home. It is to understand exactly what you are buying, what remains to be completed and what the full cost is likely to be.

My usual approach is to compare both options at the same time: resale homes in the locations the buyer actually wants and new-construction opportunities at a similar all-in budget. That comparison normally makes the trade-offs much clearer.


Get the New-Construction Buyer Checklist

Thinking about buying a new-construction or resale home in Edmonton or the surrounding area?

Contact me for my new-construction buyer checklist and a side-by-side comparison of what your budget can buy in both markets.

Call or text: 780-220-8449
Email: jay@jaysells.ca
Website: jaysells.ca

Contact me before registering online or visiting a builder if you want your own representation. Builder cooperation and registration policies vary.


Get my free New-Construction Buyer Checklist

Thinking about a new build? My free, printable 2-page checklist covers what to check at every stage, from your first show home visit to your one-year warranty.

Get the free checklist →

Frequently Asked Questions

Is there GST on a resale home in Alberta?

Most sales of previously occupied residential homes are exempt from GST. Exceptions can apply, including certain substantially renovated properties and unusual transactions. Obtain professional advice if the property’s tax status is uncertain.

Do buyers always pay the full 5% GST on a new home?

No. Eligible buyers may qualify for the existing GST/HST New Housing Rebate, the First-Time Home Buyers’ GST/HST Rebate or another applicable housing rebate. The builder’s advertised price may also include GST and assume assignment of a rebate. Review the contract and confirm eligibility before relying on any rebate.

What warranty comes with a new home in Alberta?

Most qualifying new homes require minimum coverage of one year for labour and materials, two years for delivery and distribution systems, five years for the building envelope and ten years for major structural components. Coverage has conditions, exclusions and limits.

Does warranty coverage transfer when a newer home is resold?

Yes. Alberta states that the new-home warranty is attached to the home, not the owner, and remains in effect after resale until the applicable coverage expires.

How long does an Edmonton new home take to build?

There is no single reliable timeline for every home. It depends on the builder, permits, construction type, design selections, labour, materials, weather and contract. Ask for the builder’s current written estimate and review what the agreement permits if possession is delayed. Quick-possession homes are generally available sooner because construction is already underway or complete.

Can buyers negotiate with an Edmonton home builder?

Terms vary by builder, project, property and market conditions. Buyers can ask about the price, lot premium, included specifications, upgrades, appliances, landscaping, closing costs and current incentives. Compare the net value of the complete package rather than focusing only on a price reduction.

Where is new construction happening around Edmonton?

New construction is found around Edmonton’s outer south, southwest, west, southeast, northeast and north edges, through infill projects in established neighbourhoods, and in surrounding municipalities. Current availability varies by builder and housing type.

Is an inspection worthwhile on a new home?

Yes. A new-home warranty does not eliminate the value of inspections, walkthroughs and a detailed written deficiency list. Inspection opportunities depend on the builder contract and construction stage, so buyers should clarify their rights before signing.

Should I choose new construction or resale in 2026?

Choose based on the total cost, desired location, timeline, condition, warranty, included features and your comfort with construction uncertainty. The best decision normally comes from comparing actual homes in both categories rather than comparing general assumptions.


Sources and Important Information

This article provides general information only and is not legal, tax, accounting, engineering, inspection or mortgage advice. Real-estate market statistics, mortgage rates, builder inventory, incentives and government programs can change. Confirm information that applies to your transaction with the appropriate qualified professional.

If you're comparing your options or planning a move in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, I can help you understand how the details fit into the bigger picture. With more than 25 years in new construction, on the trades and sales sides, I bring a builder’s-eye perspective to the buying process.

Call or text Jay Lewis at 780-220-8449

Jay Lewis | REALTOR® | RE/MAX Excellence

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.

Read

30-Year Mortgage in Alberta (2026): Who Qualifies?

Can You Get a 30-Year Mortgage in Alberta? 2026 Rules Explained

Short answer: Yes. A 30-year mortgage may be available in Alberta for first-time home buyers, buyers purchasing a newly built home, and some buyers with a down payment of 20% or more. A longer amortization lowers your monthly payment, but you usually pay more interest over the life of the mortgage.

By Jay Lewis, REALTOR® | RE/MAX Excellence · Updated October 21, 2026

This article is part of my Edmonton New Construction Buyer’s Guide.

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty, including the financing questions to ask your lender and builder.

If your down payment is less than 20%, the maximum amortization for an insured mortgage is generally 30 years when you are a first-time buyer and/or purchasing a new build. Otherwise, the insured-mortgage maximum is generally 25 years.

If your down payment is 20% or more, mortgage insurance is generally not required and the lender determines the maximum amortization available. That means a 30-year mortgage is not limited only to high-ratio or insured borrowers.

A longer amortization lowers the required monthly payment but generally increases the total interest paid and slows the rate at which you build equity.

What Is a First-Time Homebuyer?

For this mortgage-insurance program, you may be considered a first-time homebuyer if you meet at least one of the following conditions:

  • You have never purchased a home in Canada.

  • During the current calendar year and previous four calendar years, you did not occupy a Canadian home owned by you or your current spouse or common-law partner.

  • You have lived separately from your spouse or common-law partner for at least 90 days because of a relationship breakdown and meet the applicable timing requirements.

These definitions are specific to the mortgage-insurance program. Other programs, including the FHSA, Home Buyers’ Plan and First-Time Home Buyers’ GST/HST Rebate, have their own eligibility rules.

Can a Repeat Buyer Get a 30-Year Mortgage on a New Build?

Potentially, yes.

A repeat buyer may qualify when purchasing a home that is newly built and has not previously been occupied for residential purposes. That could include a newly completed detached home, duplex, townhouse or condominium that meets the insurer and lender requirements.

For a new condominium, CMHC makes an exception for certain periods of interim occupancy before the condominium declaration is registered or before the buyer formally takes possession.

This makes the program relevant not only to first-time buyers but also to existing homeowners moving into new construction.

How Much Down Payment Is Required?

For an owner-occupied property containing one or two units, the minimum equity requirements are generally:

  • 5% of the first $500,000

  • 10% of the portion above $500,000

For example, the minimum down payment on a $700,000 home would be:

  • 5% of the first $500,000: $25,000

  • 10% of the remaining $200,000: $20,000

  • Total minimum down payment: $45,000

Homes priced at $1.5 million or more are not eligible for CMHC mortgage insurance and generally require at least 20% down.

Mortgage default insurance is normally required when the down payment is less than 20%. The insurance protects the lender, not the homebuyer, and its premium is typically added to the mortgage.

How Much Can a 30-Year Mortgage Lower the Payment?

Here is a simplified illustration using a $450,000 mortgage and a 4.5% interest rate:

AmortizationApproximate monthly paymentApproximate total interest
25 years$2,491$297,188
30 years$2,269$366,829

In this example, the 30-year amortization lowers the payment by approximately $222 per month, but adds approximately $69,641 in interest if the same interest rate continued for the entire amortization.

This illustration excludes mortgage-insurance premiums, property taxes, utilities and other ownership costs. Canadian mortgages are renewed periodically, so the actual interest paid will depend on future rates, payment changes and how quickly the mortgage is repaid.

Does Mortgage Insurance Cost More With a 30-Year Amortization?

It can.

CMHC’s published Home Start premiums are slightly higher than its standard 25-year CMHC Purchase premiums at comparable loan-to-value levels.

For example:

Loan-to-value ratioStandard CMHC Purchase30-year CMHC Home Start
80.01% to 85%2.80%3.00%
85.01% to 90%3.10%3.30%
90.01% to 95%4.00%4.20%

The premium is a one-time mortgage-insurance charge that can generally be added to the insured mortgage amount.

Other mortgage insurers and lenders may have different products, requirements and premiums. Ask your mortgage professional to compare the complete cost, not just the monthly payment.

Will a 30-Year Amortization Help Me Qualify?

A longer amortization produces a lower scheduled mortgage payment, which may improve affordability calculations. It does not eliminate the mortgage stress test or guarantee approval.

For CMHC-insured mortgages, the published maximum debt-service ratios are generally:

  • Gross Debt Service ratio: 39%

  • Total Debt Service ratio: 44%

The qualifying calculation uses the greater of:

  • The contract mortgage rate plus 2%; or

  • 5.25%

At least one borrower or guarantor must generally have a minimum credit score of 600, although the lender and insurer will consider the entire application.

Income, existing debts, property taxes, heating costs, condominium fees, down payment and credit history can all affect approval.

Is a 30-Year Mortgage Better Than a 25-Year Mortgage?

It depends on the buyer’s priorities.

A 30-year amortization may be helpful when:

  • A lower required payment creates needed monthly flexibility.

  • The buyer is purchasing a new build and expects additional expenses after possession.

  • The buyer plans to make extra payments when their budget permits.

  • The lower payment helps keep total housing costs manageable.

A 25-year amortization may be better when:

  • The buyer can comfortably afford the higher payment.

  • Paying less total interest is the priority.

  • The buyer wants to build equity faster.

  • The slightly lower mortgage-insurance premium is meaningful.

The safest approach is to compare the payment, insurance premium and long-term interest under both options.

Can You Combine a 30-Year Mortgage With the New GST Rebate?

Potentially, yes.

The 30-year insured-mortgage rules and the First-Time Home Buyers’ GST/HST Rebate are separate programs. A qualifying first-time buyer purchasing a qualifying new home may be eligible for both.

Under the GST rebate, eligible first-time buyers may recover up to 100% of the federal GST paid on a qualifying new home valued at $1 million or less, to a maximum rebate of $50,000. A partial rebate may be available between $1 million and $1.5 million.

Read more: What Is the GST Rebate on a New Home in Alberta? (2026 Update)

Qualification for one program does not automatically mean you qualify for the other. Confirm both separately.

Questions to Ask Before Choosing a 30-Year Mortgage

Ask your mortgage professional:

  • Do I qualify because I am a first-time buyer, because the home is newly built, or both?

  • What will my mortgage-insurance premium be?

  • How much will the 30-year option reduce my monthly payment?

  • How much additional interest could I pay?

  • Can I make lump-sum or increased payments without penalties?

  • What rate and payment should I prepare for at renewal?

  • How will property taxes, condominium fees and heating costs affect qualification?

  • Can I combine this financing with the new-home GST rebate, FHSA or Home Buyers’ Plan?

Get my free New-Construction Buyer Checklist

Thinking about a new build? My free, printable 2-page checklist covers what to check at every stage, from your first show home visit to your one-year warranty.

Get the free checklist →

Frequently asked questions

Who can get a 30-year mortgage in Alberta?

With less than 20% down, first-time buyers and buyers of a newly built home can generally get a 30-year insured mortgage. With 20% or more down, mortgage insurance usually isn’t required and the lender sets the maximum amortization.

Does a 30-year mortgage cost more?

Usually, yes. The monthly payment is lower, but you pay more interest over time, and CMHC’s 30-year Home Start premiums are slightly higher than its standard 25-year premiums.

Can I use a 30-year mortgage with the new-home GST rebate?

Possibly. They’re separate programs, so a qualifying first-time buyer of a qualifying new home may be eligible for both. Check each one on its own.

Buying a New-Construction Home in the Edmonton Area?

Financing is only one part of a new-build purchase. Buyers should also understand the builder’s specifications, upgrade pricing, deposits, construction timeline, GST treatment, closing adjustments, inspection rights and warranty coverage.

If you're comparing your options or planning a move in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, I can help you understand how the details fit into the bigger picture. With more than 25 years in new construction, on the trades and sales sides, I bring a builder’s-eye perspective to the buying process.

Call or text Jay Lewis at 780-220-8449

Jay Lewis | REALTOR® | RE/MAX Excellence

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.

This article provides general information only and is not mortgage, financial, tax or legal advice. Mortgage products, qualification requirements and interest rates can change. Confirm your specific options with a licensed mortgage professional, lender and real-estate lawyer.

Official Sources

Information reviewed and updated September 4, 2026.

Read

You Can Buy a Home the Year You Graduate High School in Edmonton — Here's What That Actually Looks Like

Short answer: Yes. In Alberta you can buy a home and sign a mortgage at 18. With Edmonton condo apartments averaging $214,521 in July 2026, the minimum 5% down payment is about $10,700, plus closing costs. Qualifying for the mortgage is the harder part, because lenders want steady income and a credit history, so many young buyers start with an FHSA or buy with a co-signer.

By Jay Lewis, REALTOR® | RE/MAX Excellence · Updated October 21, 2026

Most 18-year-olds don't think about homeownership. They're thinking about summer jobs, maybe college in the fall, or figuring out what comes next. But here's something worth knowing: in Alberta, you can legally purchase a home the day you turn 18, and in Edmonton specifically, the math of doing so is closer to realistic than most people would guess. This isn't a pitch to skip university and buy a condo. It's a look at what the numbers actually say, so you, or someone you care about, can make an informed decision.

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty.

The Price Point That Makes Edmonton Different

Edmonton apartment condos averaged $214,521 in July 2026. That's not a typo, and it's not a rough neighbourhood, it's the city-wide average across all condo sales. On a home in that range, the minimum down payment required in Canada is 5%, which works out to about $10,700. Closing costs in Edmonton, legal fees, home inspection, title insurance, typically run $3,000 to $5,000. So the realistic all-in number to get keys in hand is somewhere around $15,000 to $16,000.

That's a number a determined 18-year-old with a year or two of working can actually reach. Compare that to the same calculation in Vancouver or Toronto, where a condo routinely starts above $600,000, and Edmonton's advantage becomes very clear.

The FHSA Is the Most Important Account a Graduate Can Open

The First Home Savings Account is the piece of this puzzle most young people haven't heard of yet, and it's worth understanding immediately. Starting at age 18, you can contribute $8,000 per year into an FHSA, up to a $40,000 lifetime limit. Contributions are tax-deductible (like an RRSP), and withdrawals for a first home are completely tax-free (like a TFSA). It's the best of both worlds in one account.

If you open an FHSA at 18 and contribute the full $8,000 in year one, you've already got a meaningful head start on your down payment, and you've reduced your taxable income at the same time. Stack that with the RRSP Home Buyers' Plan, which lets first-time buyers withdraw up to $60,000 from their RRSPs toward a purchase and repay it over 15 years, and the federal Home Buyers' Amount, a non-refundable tax credit on up to $10,000 of the purchase. Alberta adds one more advantage: no land transfer tax. Most provinces charge 1 to 2% of the purchase price at closing. In Alberta you pay land titles registration fees instead: a small base fee plus $5 for every $5,000 of value to register the transfer, and the same again to register the mortgage. On a $500,000 home, the transfer alone comes to about $550.

The Real Challenge Isn't the Down Payment, It's the Mortgage

The down payment is achievable. Getting approved for a mortgage at 18 is the harder part. With less than 20% down, your mortgage needs default insurance, and CMHC's rules set the bar. At least one borrower generally needs a credit score of 600 or higher. Your housing costs generally can't be more than 39% of your gross income, and all your debts together can't be more than 44%. Those ratios are tested at the higher of your contract rate plus 2% or 5.25%, so you qualify at a rate above the one you'll actually pay. Lenders will also want income they can document. How much income that takes depends on the rate, the condo fees and the property taxes, so have a mortgage professional run your numbers.

That's not impossible for a recent grad with a full-time job, especially in Alberta's trades, energy, or tech sectors, where starting wages can be enough. But it does mean the path to an 18-year-old buying solo is narrow. The more common version of this story involves a parent or family member co-signing the mortgage, which uses the co-signer's income and credit to help qualify while the young buyer builds their own history. Done carefully, this can work well, and it's worth a conversation with a mortgage professional to understand the implications for both parties.

Get my free New-Construction Buyer Checklist

Thinking about a new build? My free, printable 2-page checklist covers what to check at every stage, from your first show home visit to your one-year warranty.

Get the free checklist →

What the Smartest Move Looks Like Right Now

If you're graduating this year and homeownership is somewhere in your thinking, the single best thing you can do today, before you buy anything, is open an FHSA and start contributing. Even $2,000 or $3,000 in the account this year means you're building tax-sheltered savings, establishing a financial record, and preserving future contribution room. Get a credit card with a small limit and pay it off in full every month. These two moves, started at 18, put you in a genuinely strong position by 20 or 21.

Edmonton is one of the few cities in Canada where this timeline is realistic rather than theoretical. The entry price point is real. The programs exist. The math can work. If you want to sit down and map out what a path to ownership could look like for your specific situation, that's a conversation I'm always glad to have.

Jay Lewis, Realtor | Edmonton & Area | Alberta Real Estate


Frequently asked questions

Can an 18-year-old buy a house in Alberta?

Yes, Alberta's age of majority is 18, so a new graduate can legally purchase property and sign a mortgage the day they turn 18. The bigger hurdle is typically mortgage qualification, which requires documented income and a credit history.

How much do you need to buy a condo in Edmonton right out of high school?

Edmonton condos averaged $214,521 in July 2026, making the minimum 5% down payment roughly $10,700. Add $3,000 to $5,000 in closing costs and you're looking at approximately $15,000 to $16,000 total to get started, one of the lowest entry points of any major Canadian city.

What is the First Home Savings Account and when should a grad open one?

The FHSA lets first-time buyers contribute up to $8,000 per year (lifetime max $40,000), with tax-deductible contributions and completely tax-free withdrawals for a home purchase. New grads should open one as soon as they turn 18, the earlier you start, the more tax-sheltered savings you accumulate before you buy.


If you're comparing your options or planning a move in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, I can help you understand how the details fit into the bigger picture. With more than 25 years in new construction, on the trades and sales sides, I bring a builder’s-eye perspective to the buying process.

Call or text Jay Lewis at 780-220-8449

Jay Lewis | REALTOR® | RE/MAX Excellence

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.


Sources: Canada Revenue Agency: First Home Savings Account · Canada Revenue Agency: Home Buyers' Plan · Canada Revenue Agency: Home buyers' amount · CMHC: mortgage loan insurance requirements · REALTORS® Association of Edmonton: July 2026 market statistics · Government of Alberta: land titles registration fees

This article is general information, not financial, tax or mortgage advice. Prices change often with market conditions and world events, and these figures are estimates only. Confirm your own situation with a mortgage professional.

Read

Rates Held, Inventory Up: Why Fall 2026 Is One of Edmonton's Most Balanced Markets in Years

Short answer: Edmonton is heading into fall 2026 with a combination buyers haven’t had in some time: more inventory, slower sales and a Bank of Canada policy rate that has now held at 2.25% for seven consecutive announcements.

By Jay Lewis, REALTOR® | RE/MAX Excellence · Updated October 21, 2026

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty.

On September 2, the Bank of Canada held its policy rate at 2.25% again. At the same time, Edmonton’s August housing numbers showed 2,143 residential sales, down 9.8% from a year earlier, while inventory was 15.1% higher year over year. The average residential selling price was $469,602, up 1.8% year over year, while the MLS® HPI composite benchmark price was $426,900, down 0.6% from August 2025.

That does not mean every part of Edmonton is suddenly a buyer’s market. It does mean buyers generally have more choice and the market has become more balanced than it was during tighter periods. For sellers, accurate pricing and understanding the competition matter more.

What “Balanced” Actually Means Right Now

August brought a noticeable shift in the Greater Edmonton Area. Residential sales fell to 2,143, down 9.8% from August 2025, while inventory finished the month 15.1% higher than a year earlier. There were 3,769 new listings during the month.

That works out to roughly a 57% sales-to-new-listings ratio for August. More importantly for buyers, there are simply more properties competing for attention than there were a year ago. That can mean more time to compare homes, more opportunities to include appropriate conditions and, on some properties, more room to negotiate.

Prices, however, are not moving uniformly downward. The average residential selling price was $469,602, up 1.8% year over year, while the MLS® HPI composite benchmark price was $426,900, down 0.6% year over year. Detached homes averaged $575,575, up 1.0% year over year, while row/townhouses and apartment condominiums were both down 1.2% year over year.

The takeaway is not that every Edmonton property has suddenly become a bargain. It is that buyers have more choice while pricing has become much less uniform. Property type, neighbourhood, condition and seller motivation matter more in this kind of market.

One small but important improvement there: I’m explicitly saying Greater Edmonton Area because those RAE statistics cover the GEA, not just the City of Edmonton.

The Rate Picture and What It Means for Your Mortgage

The Bank of Canada held its policy rate at 2.25% on September 2, 2026, continuing the pause that began after the October 2025 cut. The Bank said economic growth has improved, but inflation risks have increased because of persistent energy costs and new trade pressures. Its next scheduled rate decision is October 28, 2026.

For buyers, the important point is that mortgage rates do not all move exactly with the Bank of Canada’s policy rate. Variable mortgage rates are closely influenced by lenders’ prime rates, while fixed mortgage pricing can move with broader funding costs and bond yields. That means a Bank of Canada hold does not necessarily mean every mortgage rate will stay unchanged.

If you're buying this fall, compare the actual rate, payment, amortization and qualification rules available to you rather than waiting for a particular Bank of Canada announcement.

If you're considering a 30-year amortization, see my 2026 guide to 30-year mortgages in Alberta for the current eligibility rules and payment trade-offs.

What Fall Usually Means for Edmonton Real Estate

Edmonton real estate is seasonal, but buyers and sellers should be careful about assuming every fall will behave the same way.

Spring typically brings the highest level of activity, while summer and fall can bring changes in both listing volume and buyer urgency. By September, some buyers who paused during the summer return to the market, while sellers who remain listed may become more focused on securing a sale before winter.

This fall, buyers are also entering a market with more resale inventory and a substantial pipeline of new housing. CMHC says Edmonton’s housing market moderated in the first half of 2026 after two years of record construction, but construction activity remains above historical averages.

At the same time, Alberta continues to grow. Statistics Canada reported that Alberta had the fastest population growth rate among the provinces from July 2025 to July 2026, at 1.5%, although growth has slowed compared with the previous year.

For buyers and sellers, the important point is not that fall automatically favours one side. It is that more supply means pricing, property quality and local competition matter more than they did when inventory was tighter.

What This Means If You’re Thinking of Moving

For buyers, the combination of higher inventory and slower sales means there may be more opportunities to compare homes carefully, negotiate appropriate terms and avoid feeling rushed into the first acceptable property.

For sellers, the market is still active, but buyers have more alternatives. Pricing accurately, presenting the home well and understanding competing listings in your immediate area matter more when inventory is higher.

For anyone considering new construction, compare builder pricing against resale options using the all-in cost, including the lot, GST treatment, upgrades, landscaping, appliances and anything else needed after possession.

The Edmonton market is not moving in one direction across every neighborhood and property type. The best decisions come from looking at the specific segment you are buying or selling in, not just the citywide headline.

Get my free New-Construction Buyer Checklist

Thinking about a new build? My free, printable 2-page checklist covers what to check at every stage, from your first show home visit to your one-year warranty.

Get the free checklist →

Frequently Asked Questions

Is Fall 2026 a Good Time to Buy a Home in Edmonton?

Fall 2026 is giving many Edmonton-area buyers more choice than they had a year ago. In August, Greater Edmonton Area inventory was 15.1% higher year over year, while residential sales were 9.8% lower. That can create more time to compare properties and, depending on the home, more negotiating room.

Whether it is a good time for you depends on your financing, timeline, preferred neighborhood and the specific property, not simply whether the overall market is labelled a buyer’s or seller’s market.

Are Edmonton Home Prices Falling in 2026?

The picture is mixed. In August, the average residential selling price was $469,602, up 1.8% year over year, while the MLS® HPI composite benchmark price was $426,900, down 0.6% year over year. Different property types and neighborhoods can move differently, so one citywide number does not tell the whole story.

What Is the Bank of Canada Rate Right Now?

The Bank of Canada held its policy rate at 2.25% on September 2, 2026. Its next scheduled rate announcement is October 28, 2026.

Mortgage rates do not all move directly with the policy rate, so buyers should compare the actual fixed and variable options available to them rather than assuming a Bank of Canada hold means every mortgage rate will remain unchanged.

Will the Bank of Canada Cut Rates Again in 2026?

That is uncertain. The Bank’s September statement described competing risks involving economic growth and inflation, so I would not tell buyers that another cut, or no cut, is certain.

For a home purchase, it is generally more useful to make sure the numbers work at the mortgage terms available today rather than base the decision on trying to predict the next rate announcement.

Does More Inventory Mean Edmonton Is a Buyer’s Market?

Not necessarily across the entire market. Higher inventory and slower sales can create more buyer-friendly conditions, but the amount of negotiating power varies by neighbourhood, property type, price range and the individual seller’s situation.

Thinking About Buying or Selling in the Edmonton Area?

If you're considering a move in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, I can help you understand how current inventory, pricing and financing conditions apply to your specific situation.

With more than 25 years in new construction, on the trades and sales sides, I bring a builder’s-eye perspective to the buying and selling process.

Call or text Jay Lewis at 780-220-8449

Jay Lewis | REALTOR® | RE/MAX Excellence

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.
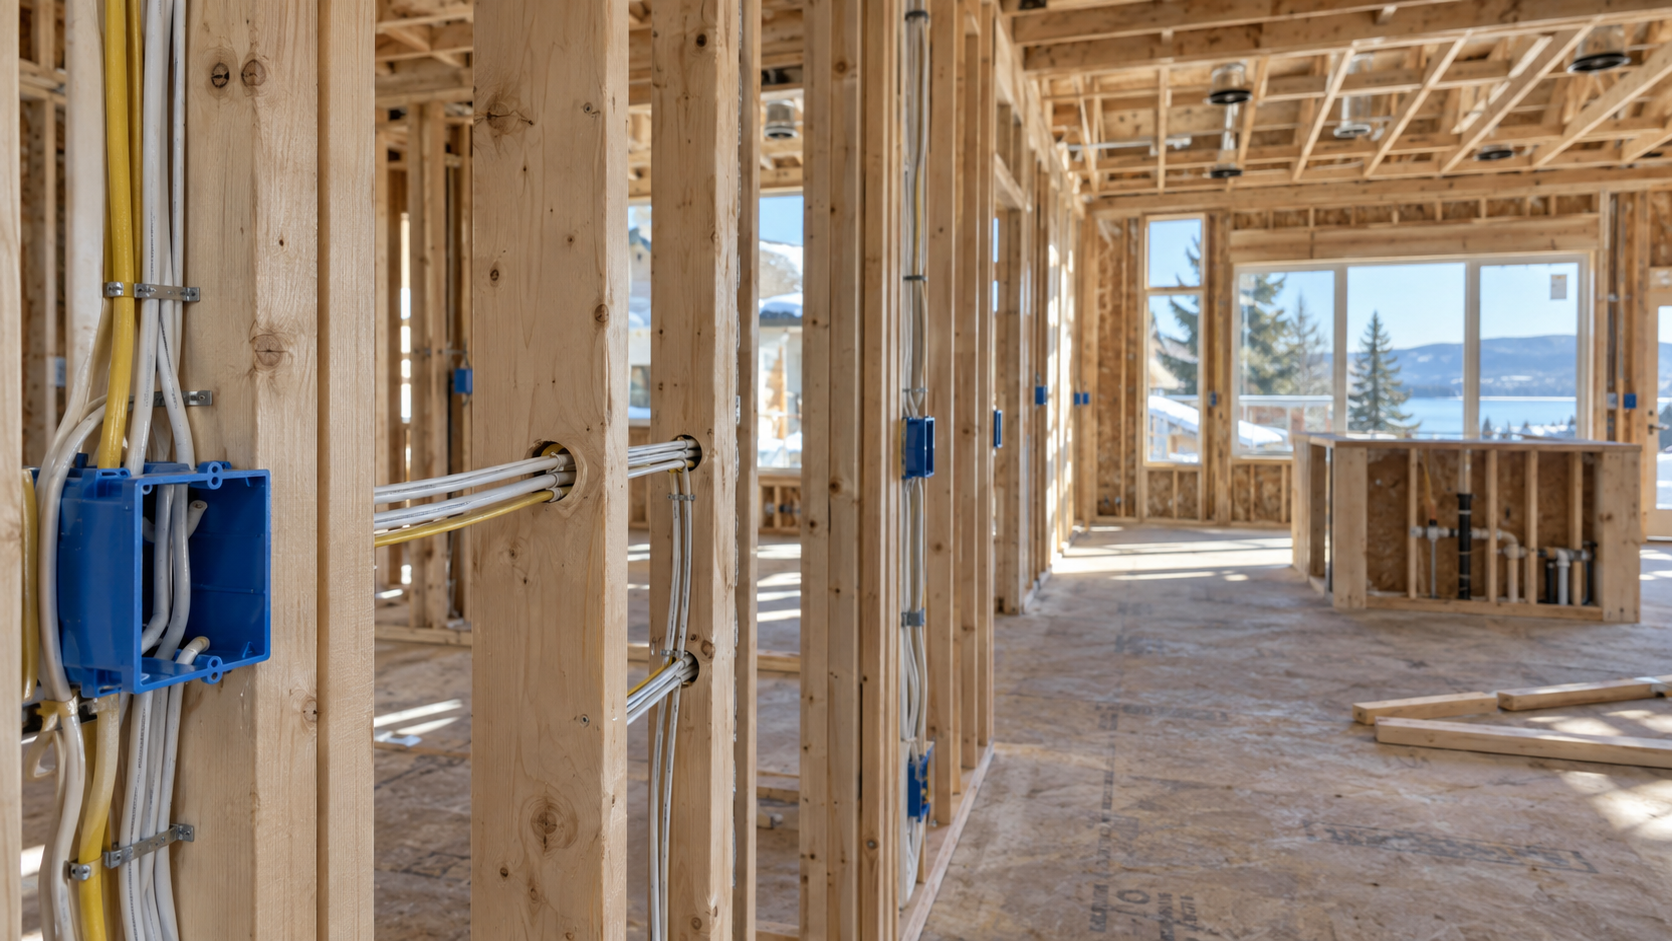
Disclaimer

This article provides general information only and is not legal, financial, tax, mortgage or other professional advice. Rules, programs, market conditions and eligibility requirements can change. Confirm your specific circumstances with the appropriate professional or government agency.

Official Sources

Information reviewed and updated September 23, 2026.


Read

Glenora and a Balanced Market: What Edmonton Buyers Need to Know This August

Short answer: In July 2026 the Greater Edmonton Area moved into a balanced market. Sales were down 11.0% from a year earlier and homes took about 39 days to sell, so buyers had more room to negotiate. In Glenora, listings averaged around $1.34 million, from about $650,000 for an original character home to over $2 million for a new custom build on the crescents.

By Jay Lewis, REALTOR® | RE/MAX Excellence · Updated October 21, 2026

The most interesting thing happening in Edmonton real estate right now isn't a bidding war, it's the quiet return of choice. For the first time in several years, buyers in the Greater Edmonton Area have genuine leverage, and the numbers back it up. That shift has implications for every price point in the city, including some of Edmonton's most storied neighbourhoods.

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty.

The Market Has Officially Found Its Balance

July 2026 data from the REALTORS® Association of Edmonton tells a clear story: 2,535 homes sold in the month, down 11.0% from July 2025, while new listings rose 0.6% year over year to 4,258. That combination pushed months of supply above the three-month threshold, the traditional marker of a balanced market. The sales-to-inventory ratio sits at 31%, and homes are now taking an average of 39 days to sell, six days longer than this time last year.

What does that mean practically? Sellers are still selling, the average price across all property types came in at $475,079 in July, about 2.6% above last year, but they're doing it with less urgency and more negotiation. The era of waiving every condition and submitting blind is, at least for now, behind us.

Mortgage Rates Are Stable, But Not Declining

The Bank of Canada held its policy rate at 2.25% on July 15th, marking the sixth consecutive hold. The last rate cut was back in October 2025, and markets are currently pricing in no changes through the end of 2026. That puts the prime rate at 4.45%, with the best 5-year fixed mortgages in Alberta available around 4.24% from major lenders.

The stability is useful. Buyers who've been waiting for rates to drop further may be waiting a while, but the current environment is workable, particularly in a balanced market where there's room to negotiate on price and conditions rather than competing purely on speed. If you haven't already had a mortgage pre-approval conversation, now is a good time, especially since fixed rates are projected to drift slightly higher, toward 4.32%, by year's end.

Neighbourhood Spotlight: Glenora

If you've ever walked the tree-lined crescents between 102nd Avenue and the North Saskatchewan River valley, you already understand Glenora's appeal. One of Edmonton's oldest and most beloved communities, Glenora has managed to hold its character, mature canopy trees, wide streets, heritage homes from the early 1900s, while remaining close to downtown and the river valley trail system.

The numbers reflect that desirability. The average home listing price in Glenora sits around $1,339,000, which is roughly 154% above Edmonton's city-wide average. That range is wide, though: original character homes can enter at around $650,000, while fully renovated or new custom builds on the prime crescents regularly clear $2 million. There's also a condo segment averaging around $531,000 for buyers who want the neighbourhood without the lot-maintenance commitment.

Glenora isn't for every buyer's budget, but it's worth understanding what drives its value, community infrastructure, mature landscaping, proximity to the Glenora Community League and its park, splash park, and programming, and a stability that comes from being one of the most in-demand addresses in the city for generations. In a balanced market, even Glenora properties may be sitting a bit longer than they were a year ago, which is precisely when thoughtful buyers should be paying attention.

Get my free New-Construction Buyer Checklist

Thinking about a new build? My free, printable 2-page checklist covers what to check at every stage, from your first show home visit to your one-year warranty.

Get the free checklist →

Frequently asked questions

Is Edmonton a balanced market?

In July 2026 it moved into balanced territory. Months of supply rose above three, sales were down 11.0% from a year earlier and homes took about 39 days to sell.

How much do homes cost in Glenora?

When I wrote this, Glenora listings averaged around $1.34 million. Original character homes started around $650,000, renovated or new custom homes on the prime crescents went over $2 million, and condos averaged around $531,000.

Did the Bank of Canada change rates in July 2026?

No. It held its policy rate at 2.25% on July 15, 2026.

What This All Adds Up To

August is historically slower, summer always is, but the underlying conditions are genuinely more favorable for buyers than they've been in recent memory. Inventory is up, days on market are longer, and the rate environment isn't the emergency it felt like at the peak. If you've been watching Edmonton real estate from the sidelines, the current window is worth a serious conversation.

Whether you're curious about a specific neighbourhood like Glenora, want to understand what a pre-approval actually gets you right now, or just want someone to walk you through the process without any pressure, I'm always happy to chat.

If you're comparing your options or planning a move in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, I can help you understand how the details fit into the bigger picture. With more than 25 years in new construction, on the trades and sales sides, I bring a builder’s-eye perspective to the buying process.

Call or text Jay Lewis at 780-220-8449

Jay Lewis | REALTOR® | RE/MAX Excellence

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.
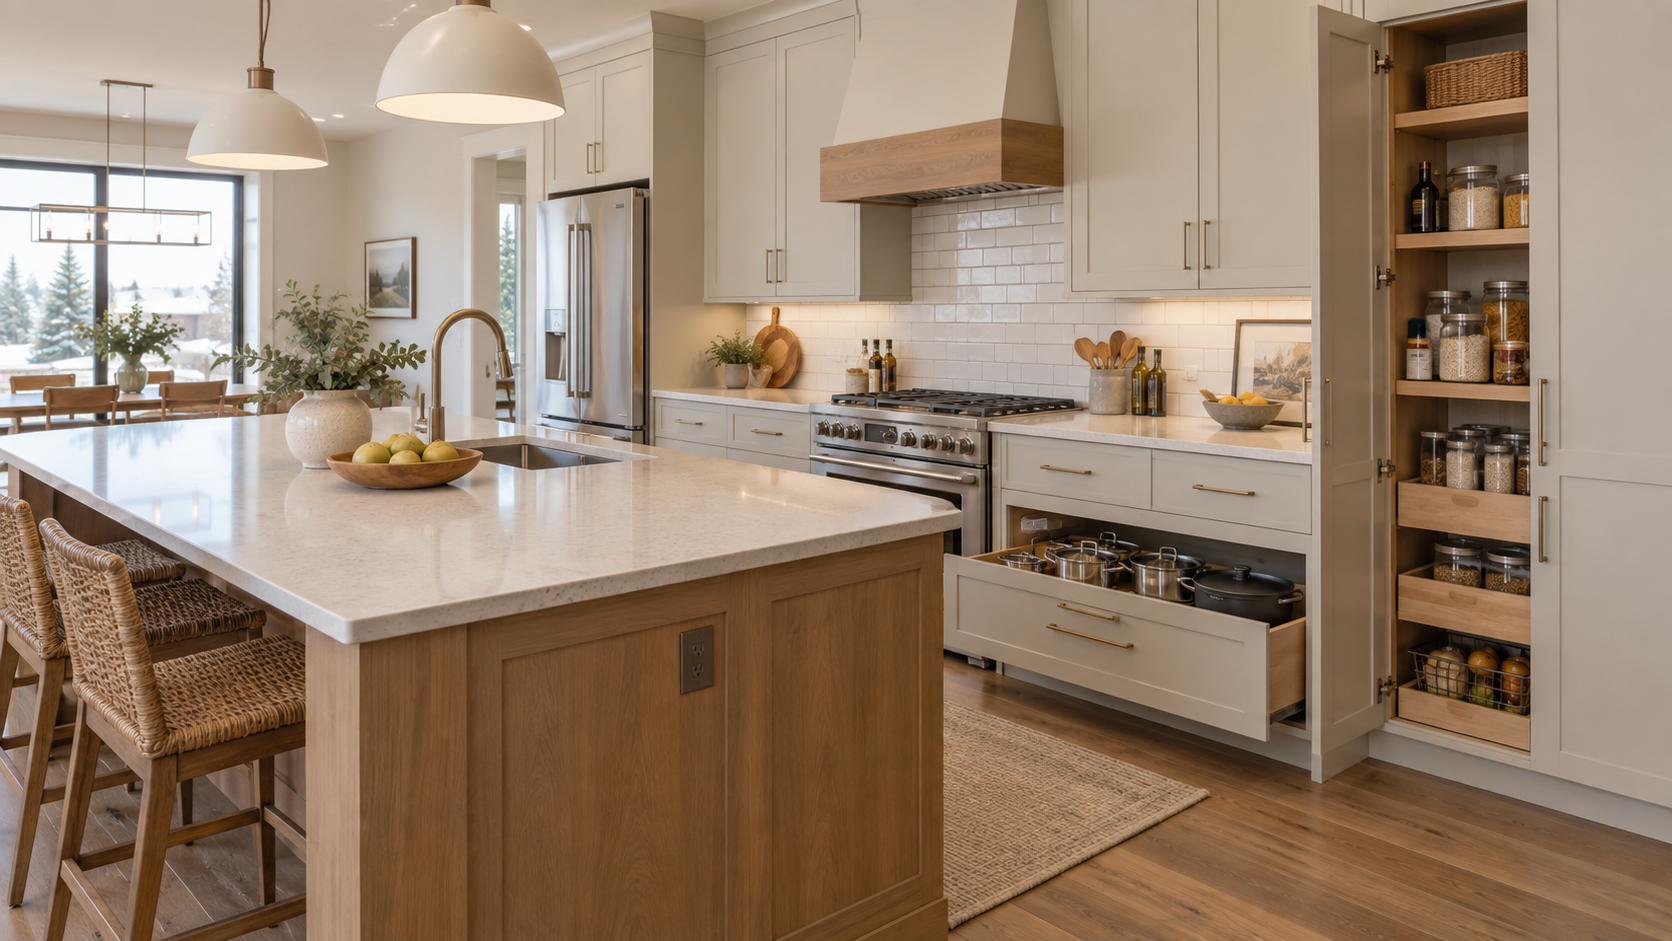

Sources: REALTORS® Association of Edmonton: July 2026 market statistics · Bank of Canada: July 15, 2026 rate decision

This article is general information, not financial or mortgage advice. Prices change often with market conditions and world events, and these figures are estimates only.

Read

Why Wîhkwêntôwin (Formerly Oliver) Is Worth a Second Look Right Now

Short answer: Wîhkwêntôwin, the neighbourhood long known as Oliver, sits beside downtown and the river valley, and most of its homes are condos and apartments. In July 2026, condo apartments across Greater Edmonton averaged $214,521, the lowest of any property type. That makes it one of the cheaper ways to live in a walkable, central neighbourhood, and the balanced market gives buyers time to choose.

By Jay Lewis, REALTOR® | RE/MAX Excellence · Updated October 21, 2026

Here's something that surprises a lot of buyers: Edmonton's oldest neighbourhood just west of downtown recently swapped its name for a Cree term meaning "circle of friends," and the shift says almost as much about where this city is headed as it does about where it's been. Wîhkwêntôwin, the community long known as Oliver, is quietly one of the most livable and underpriced pockets in the entire metro area, and this month's market numbers give a good excuse to talk about why.

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty.

The Bigger Picture First

Greater Edmonton settled into balanced territory in July, and the numbers tell a clear story. The average home price across all property types came in at $475,079, up 2.6 percent from a year earlier but down 1.8 percent from June. The benchmark price held flat year-over-year at $429,100. Homes took an average of 39 days to sell, three days longer than June and six days longer than July 2025, and months of supply climbed to 3.2, which is the threshold where the market tips out of seller's territory and into balanced conditions. Detached homes averaged $585,726, semi-detached homes $425,329, townhouses $292,756, and condo apartments $214,521. That last number matters a lot for what comes next.

Why Wîhkwêntôwin Punches Above Its Price Point

Most of Wîhkwêntôwin's homes are condos in apartment buildings, many of them high-rises. That's a big reason it's worth a look while condo apartments across Greater Edmonton are averaging $214,521, well below every other property type. You get a neighbourhood right beside downtown and the North Saskatchewan River valley, close to Victoria Park, the Royal Glenora Club and the Victoria Golf Course, with MacEwan University and the Government Centre LRT station near enough that living without a car is realistic. There are some houses and duplexes too, but not many, so if that's what you want, expect a small selection.

What Balanced Conditions Actually Change for You

A 3.2-month supply doesn't mean much until you translate it into behaviour. For sellers, it means the days of listing on a Thursday and fielding six offers by Monday are mostly behind us, at least for now, and pricing accurately from day one matters more than it did a year ago. For buyers, it means you can ask for a proper inspection period, negotiate on closing costs, and not feel like you're racing a dozen other offers on every showing. Inventory sitting 18 percent higher than a year ago gives you room to be selective rather than reactive, which is a meaningfully different experience than the market Edmonton buyers dealt with in 2023 and 2024.

Get my free New-Construction Buyer Checklist

Thinking about a new build? My free, printable 2-page checklist covers what to check at every stage, from your first show home visit to your one-year warranty.

Get the free checklist →

The Affordability Backdrop Nobody Should Ignore

Zoom out and the numbers still lean toward buyers. The MLS® HPI composite benchmark price for Greater Edmonton was $429,100 in July 2026, unchanged from a year earlier, and inventory was 17.9% higher than in July 2025. If you're comparing notes with friends or family in other provinces, those numbers are worth keeping in mind.

Frequently asked questions

Why was Oliver renamed Wîhkwêntôwin?

The neighbourhood took a Cree name meaning "circle of friends."

What kind of homes are in Wîhkwêntôwin?

Mostly condos in apartment buildings, many of them high-rises. There are some houses and duplexes, but not many.

What did condos sell for in Edmonton in July 2026?

Condo apartments across Greater Edmonton averaged $214,521, the lowest average of any property type that month.

If you've been curious about what a neighbourhood like Wîhkwêntôwin actually costs to get into, or you just want a second set of eyes on whether now makes sense for your specific situation, I'm happy to walk through it with you, no pressure attached.

If you're comparing your options or planning a move in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, I can help you understand how the details fit into the bigger picture. With more than 25 years in new construction, on the trades and sales sides, I bring a builder’s-eye perspective to the buying process.

Call or text Jay Lewis at 780-220-8449

Jay Lewis | REALTOR® | RE/MAX Excellence

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.Jay Lewis, Realtor | Edmonton & Area | Alberta Real Estate

Sources: REALTORS® Association of Edmonton: July 2026 market statistics

This article is general information, not financial or mortgage advice. Prices change often with market conditions and world events, and these figures are estimates only.

Read

Is Edmonton's First Place Program Still Available for First-Time Buyers? (2026 Update)

Is Edmonton's First Place Program Still Available for First-Time Buyers? (2026 Update)

Short answer: No. As of a City Council decision on April 15, 2026, there are no remaining sites to be developed under Edmonton's First Place Program. The final First Place sites were developed in 2023, so the program is not currently an option for buyers looking to purchase into a new First Place development.

By Jay Lewis, REALTOR® | RE/MAX Excellence · Updated October 21, 2026

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty, including the budget and GST items first-time buyers often miss.

If you've found older articles describing First Place as an active first-time-buyer program, that information is now outdated.

What Was Edmonton's First Place Program?

The City of Edmonton launched the First Place Program in 2006 to develop townhomes on surplus school sites and make home ownership more accessible to qualifying first-time buyers.

Homes were sold at market price, while the land portion of the mortgage was deferred for five years. The land cost was deferred, not forgiven, which is an important distinction for buyers researching how the program worked. The City says the program was intended to develop up to 1,000 townhomes across 20 surplus school sites.

Who Was the First Place Program For?

Eligibility was aimed at qualifying first-time buyers purchasing a home within one of the designated First Place developments. The program included eligibility requirements and restrictions associated with the land-payment deferral.

Because there are no remaining First Place sites being developed, buyers searching in 2026 should focus on programs and incentives that are currently available instead

What Can Edmonton First-Time Buyers Use Instead in 2026?

First-time buyers still have several federal programs that may help with purchasing a home.

The First Home Savings Account (FHSA) allows eligible first-time buyers to save toward a qualifying home using a tax-advantaged account.

The Home Buyers' Plan (HBP) currently allows eligible buyers to withdraw up to $60,000 from an RRSP toward buying or building a qualifying home. Eligible buyers may also use an FHSA and the HBP for the same qualifying purchase when the requirements of both programs are met.

There is also the federal Home Buyers' Amount, a non-refundable income-tax credit available to qualifying buyers.

For buyers purchasing new construction, the First-Time Home Buyers’ GST Rebate can provide up to $50,000 in federal GST relief for qualifying buyers.


Source: City of Edmonton (edmonton.ca). This is general information only, not financial or legal advice, confirm current program availability and eligibility for any incentive directly with the relevant government source before making purchase decisions.

Get my free New-Construction Buyer Checklist

Thinking about a new build? My free, printable 2-page checklist covers what to check at every stage, from your first show home visit to your one-year warranty.

Get the free checklist →

Frequently asked questions

Is the First Place Program still available in 2026?

No. The City says there are no remaining sites to develop after a Council decision on April 15, 2026, and the last First Place sites were developed in 2023.

How did the First Place Program work?

The City built townhomes on surplus school sites. Buyers paid market price, and the land portion of the mortgage was deferred for five years. It was deferred, not forgiven.

What can first-time buyers in Edmonton use instead?

Federal programs such as the First Home Savings Account, the RRSP Home Buyers' Plan (up to $60,000) and the Home Buyers' Amount tax credit. If you're buying a new build, the First-Time Home Buyers’ GST Rebate can be worth up to $50,000.

Buying Your First Home in Edmonton or the Surrounding Area?

If you're comparing first-time-buyer programs or considering a new-construction home, I can help you understand how the available options fit into the overall purchase, not just the advertised price.

I work with buyers throughout Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove and Stony Plain.

If you're comparing your options or planning a move in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, I can help you understand how the details fit into the bigger picture. With more than 25 years in new construction, on the trades and sales sides, I bring a builder’s-eye perspective to the buying process.

Call or text Jay Lewis at 780-220-8449

Jay Lewis | REALTOR® | RE/MAX Excellence

Sources: City of Edmonton: First Place Program · Canada Revenue Agency: First Home Savings Account · Canada Revenue Agency: Home Buyers' Plan · Canada Revenue Agency: First-Time Home Buyers’ GST/HST Rebate

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.
This article provides general information only and is not financial, tax or legal advice. Program availability and eligibility requirements can change. Confirm your eligibility with the appropriate government agency, financial institution and professional advisers before making a purchase decision.

Information reviewed and updated September 23, 2026.


Read

How Much Does New Construction Cost Per Square Foot in Edmonton? (2026)

Short answer: There's no single reliable cost-per-square-foot number for new construction in Edmonton. Based on 2026 industry estimates and what I'm seeing with Edmonton-area builders, construction alone typically runs roughly $175 to $230 per square foot for entry-level finishes, $230 to $290 for mid-range and $290 to $350+ for upper-end homes. Land, lot premiums, permits, servicing, GST and upgrades can add substantially to that, so compare all-in prices, not the headline number. Prices change often with market conditions and world events, so treat any figures here as general estimates only.

By Jay Lewis, REALTOR® | RE/MAX Excellence · Updated September 30, 2026

This article is part of my Edmonton New Construction Buyer’s Guide.

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty, including what to confirm is in the price before you compare builders.

For buyers comparing builders, the more important question isn't "What's your price per square foot?" It's "What exactly am I getting for that price?" With more than 25 years in new construction, on the trades side and the sales side, I use price per square foot as a comparison tool, not a substitute for reviewing the plans, specifications, lot and included features.

What does new construction cost per square foot in Alberta in 2026?

Based on 2026 industry estimates and what I'm seeing with Edmonton-area builders, construction-only costs typically fall in these ranges, by finish level:

  • Entry level (standard finishes): about $175 to $230 per sq ft

  • Mid-range (upgraded flooring, kitchen and bathrooms): about $230 to $290 per sq ft

  • Upper range (custom millwork, high-end fixtures and appliances): about $290 to $350+ per sq ft

Land, permits, servicing and professional fees come on top of these numbers and can add substantially to the total project cost. Treat these as ballpark ranges, not quotes.

Important: construction prices change often, sometimes quickly, with market conditions and world events, including material and labour costs, interest rates, tariffs and supply-chain disruptions. The figures in this article are general estimates for comparison only. Always get current, written pricing from the builder for the specific home, lot and specifications you're considering.

A simple illustration: at $230 per square foot, a 2,000 sq ft home works out to about $460,000 for construction alone, before land, lot premiums, permits, GST and upgrades. That's why two homes with similar square footage can end up far apart in total price.

Why is a builder's price per square foot different from a custom-build estimate?

When you buy from a production builder in Edmonton, you usually pay a package price for the home and lot together, often with GST treatment and some inclusions built in. Dividing that package price by the square footage gives a different number from a construction-only estimate. It isn't wrong; it's just measuring something different. Always check what a quoted number includes before comparing it with another.

What does cost per square foot usually leave out?

Depending on the builder and project, a quoted price may exclude, or treat separately:

  • Land or the lot price, and lot premiums

  • Building permits and municipal fees

  • Site servicing, grading and drainage work

  • Landscaping and fencing

  • Decks and exterior concrete

  • Appliances and window coverings

  • Basement development

  • Design-centre upgrades

  • Financing and legal costs

  • GST

GST deserves particular attention. A builder's advertised price may already include GST, and it may also assume that an available rebate will be assigned or credited to the builder. Eligible first-time buyers of qualifying new homes may qualify for up to $50,000 in federal GST relief. See my 2026 Alberta new-home GST rebate guide for the current rules and price thresholds.

For the costs that come on top of the builder's price, like legal fees, land title registration, insurance and possession-day adjustments, see what is included in a builder base price in Edmonton.

How do I compare builder pricing properly?

Two builders can quote very different prices per square foot and still be offering homes with very different specifications, inclusions and final costs. Before comparing one builder with another, ask:

  1. Is the lot included, and is there a lot premium?

  2. Is GST included, and has any GST rebate already been assumed in the price?

  3. What flooring, cabinetry, countertops and fixtures are standard?

  4. Are appliances and air conditioning included?

  5. Are landscaping, fencing, a deck, the driveway, sidewalks and exterior concrete included?

  6. What electrical, plumbing and mechanical specifications are standard?

  7. Are there design-centre allowances, and which upgrades would you realistically choose?

  8. Are there architectural or community requirements that add cost?

  9. What closing adjustments or additional fees should you expect?

The useful comparison isn't Builder A at $240 per square foot versus Builder B at $260. It's the all-in price of two similarly equipped homes on comparable lots. For deciding which upgrades are worth it, see which new home upgrades are worth it. For what to check in the agreement, see my Alberta builder contract checklist.

Get my free New-Construction Buyer Checklist

Thinking about a new build? My free, printable 2-page checklist covers what to check at every stage, from your first show home visit to your one-year warranty.

Get the free checklist →

Frequently asked questions

How much does it cost per square foot to build a home in Edmonton in 2026?

There's no single reliable number, because it depends on the type of home, specifications, lot, site conditions and what the quoted price includes. In 2026, construction alone typically ranges from about $175 per square foot for construction alone with entry-level finishes to $350+ for upper-end homes, before land and other costs.

Does a builder's price per square foot include the lot?

Not always. Some advertised prices include the lot, while others have separate lot costs or lot premiums. Ask the builder exactly what's included before comparing the number with another home.

Is GST included in new-home prices in Edmonton?

It depends on how the builder advertises the home. GST may already be included, and the price may also assume an available GST rebate. Confirm both before comparing builders. Eligible first-time buyers may qualify for up to $50,000 through the First-Time Home Buyers' GST/HST rebate (Canada Revenue Agency).

Why can two homes with the same square footage cost so differently?

Square footage doesn't show differences in cabinetry, flooring, windows, mechanical systems, ceiling heights, structural features, lot conditions, exterior finishes or included upgrades. Two 2,000 sq ft homes can have very different construction costs.

Is new construction more expensive than resale in Edmonton?

Not right now. In the 30 days to September 28, 2026, the median new detached family home in Edmonton sold for about $289 per square foot, compared with about $308 for resale (REALTORS® Association of Edmonton MLS® data: 3+ bedrooms, 2+ full bathrooms and an ensuite). New-build prices respond to inventory: almost 600 new family homes were for sale and 81 sold, up from about 500 for sale a year earlier, and the median new home sold for about 4% less than a year ago. When new-build inventory swells, builders adjust prices and incentives; when it tightens, prices can firm up again. The new homes in that data were also larger, and many resale homes have finished basements that aren’t counted in the square footage. So compare current numbers and the whole package: price, GST, basement, upgrades and warranty. Prices change often with market conditions and world events. See new construction vs. resale in Edmonton for a full comparison.

Comparing builder pricing in the Edmonton area?

If you're comparing builders in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, I can help you look beyond the advertised price per square foot and compare the actual specifications, lot costs, upgrades and total investment. This is one of the areas where I encourage buyers to slow down. Call or text me at 780-220-8449, or book a 20-minute call.

Jay Lewis | REALTOR® | RE/MAX Excellence

Sources:Canada Revenue Agency: First-Time Home Buyers' GST/HST rebate

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.
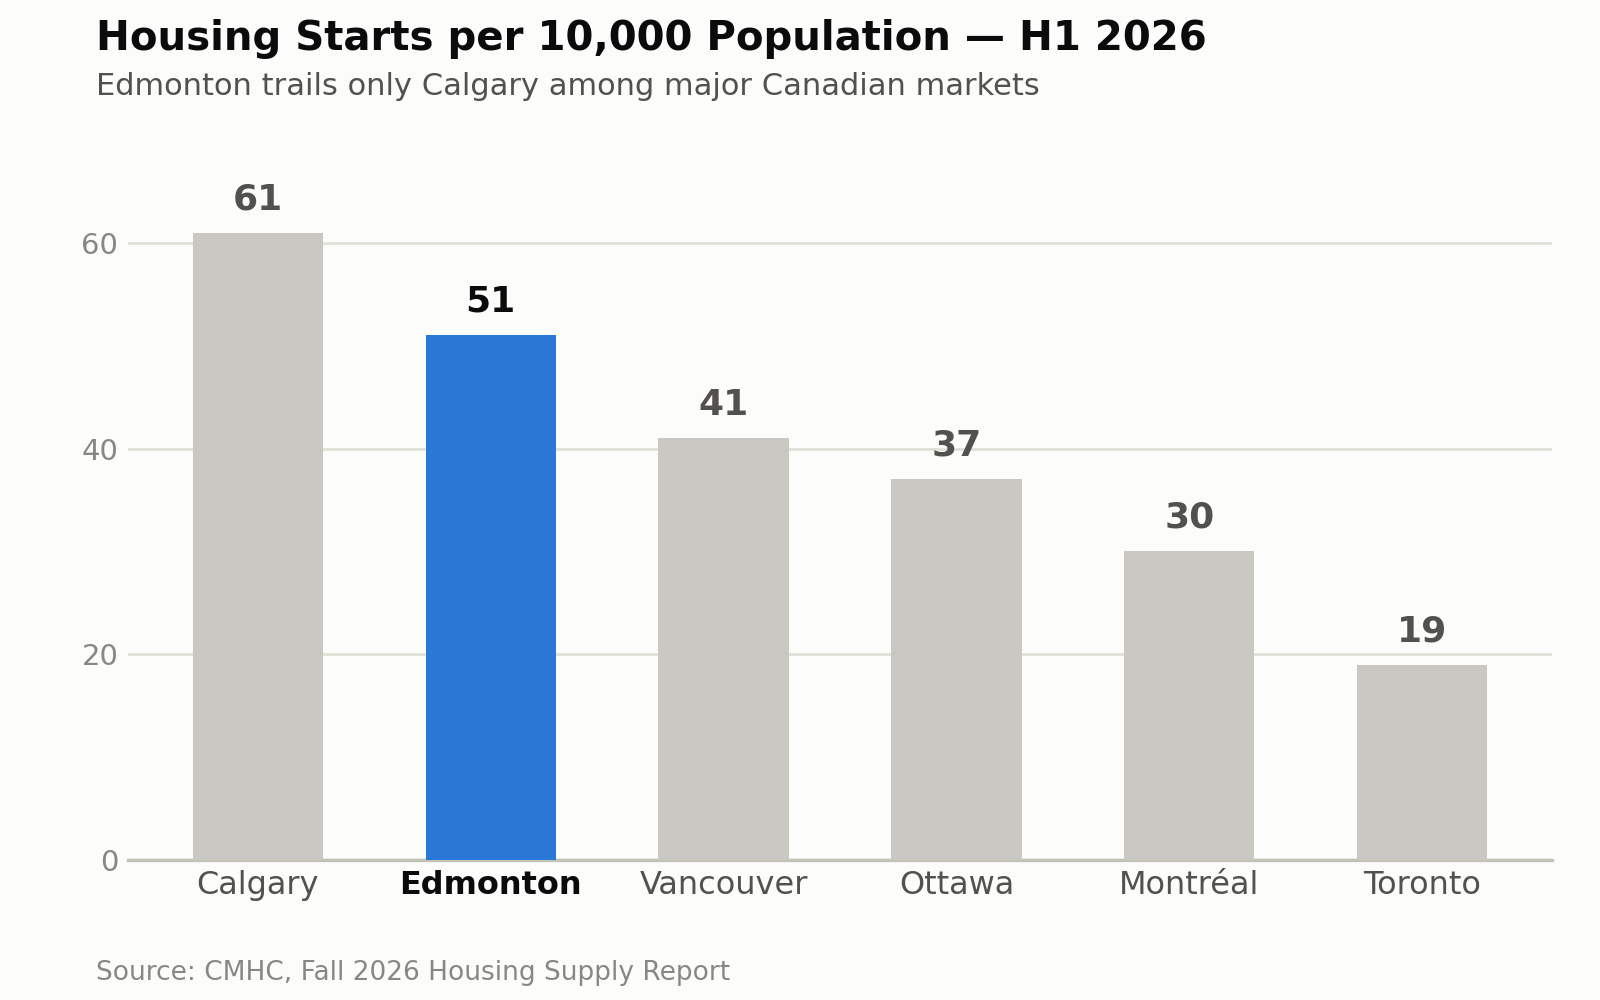
Read

New Home GST Rebate in Alberta: 2026 First-Time Buyer Guide

Short answer: Eligible first-time home buyers in Alberta may recover up to 100% of the federal GST paid on a qualifying newly built or substantially renovated home, to a maximum rebate of $50,000. The full rebate applies to homes valued at $1 million or less, and it phases out to zero at $1.5 million.

By Jay Lewis, REALTOR® | RE/MAX Excellence · Updated October 21, 2026

This article is part of my Edmonton New Construction Buyer’s Guide.

Free download: my New-Construction Buyer Checklist. Two printable pages, from your first show home visit to your one-year warranty, including the GST questions to ask before you sign.

For qualifying homes valued at $1 million or less, the rebate can recover up to 100% of the GST paid, subject to the $50,000 maximum. The rebate is gradually reduced for homes valued between $1 million and $1.5 million, and no First-Time Home Buyers' GST/HST Rebate is available at $1.5 million or more.

Applications for the rebate are now open.

GST in Alberta in 2026: quick facts

  • Alberta has no provincial sales tax, so a new home is charged only the 5% federal GST.

  • On a $600,000 new home, that is about $30,000 in GST before any rebate.

  • Eligible first-time buyers may get back up to $50,000: all of the GST on homes up to $1 million, phasing out to zero at $1.5 million.

  • If you don’t qualify, you may still get the older GST/HST New Housing Rebate, up to $6,300, on lower-priced homes.

  • Figures are general estimates; confirm your own eligibility with the CRA and your lawyer.

How Much Is the New GST Rebate in Alberta?

Alberta does not have a provincial sales tax. A taxable sale of a newly built home is generally subject to the 5% federal GST, although the builder's advertised price may already include GST.

The new First-Time Home Buyers’ GST/HST Rebate works as a top-up to the existing GST/HST New Housing Rebate. When both rebates apply, an eligible first-time buyer may recover up to 100% of the federal GST.

Qualifying home valuePotential FTHB GST rebate
$500,000Up to $25,000
$600,000Up to $30,000
$750,000Up to $37,500
$900,000Up to $45,000
$1,000,000Up to $50,000
$1,250,000Up to $25,000
$1,500,000+No FTHB rebate

Examples are illustrative. Actual rebate eligibility and calculations depend on the transaction and CRA requirements.

For example, the CRA explains that an eligible buyer purchasing a qualifying $1.25-million home, halfway between $1 million and $1.5 million, may qualify for 50% of the maximum $50,000 rebate.

The actual calculation can depend on the transaction, including how the builder’s price is stated and whether GST is already included. Buyers should confirm the calculation with the builder, CRA, an accountant and their real-estate lawyer.

What About the Existing New Housing Rebate?

The existing GST/HST New Housing Rebate remains available to eligible buyers, including some buyers who are not purchasing their first home.

For the federal portion of the existing rebate, eligible buyers can generally recover 36% of the GST paid, up to a maximum of $6,300. The rebate is gradually reduced for qualifying homes between $350,000 and $450,000 and is generally unavailable at $450,000 or more.

For qualifying first-time buyers, the new FTHB rebate acts as a top-up to the existing rebate, potentially bringing the total federal GST relief to 100%, up to the new $50,000 maximum.

CRA confirms the existing federal rebate's $6,300 maximum and the $350,000 to $450,000 phase-out.

Who Is Considered a First-Time Buyer?

Generally, a buyer must meet all the following requirements:

  • Be at least 18 years old

  • Be a Canadian citizen or permanent resident

  • Be purchasing or building the home as their primary residence

  • Not have lived in a home owned by the buyer or their spouse or common-law partner during the current calendar year or the previous four calendar years

  • Not have previously received the First-Time Home Buyers’ GST/HST Rebate

  • Have a spouse or common-law partner who has not previously received the rebate

The home can be a newly constructed or substantially renovated house purchased from a builder. Certain owner-built homes, co-operative housing shares, modular homes, mobile homes and floating homes may also qualify when the applicable CRA requirements are met.

Important Dates and Conditions

For a typical new home and land purchased together from a builder:

  • The purchase agreement must be entered into on or after March 20, 2025, and before 2031.

  • Construction or substantial renovation must begin before 2031.

  • The home must be substantially completed before 2036.

  • Ownership must transfer to the buyer before 2036.

  • The home must be purchased for use as the buyer’s primary residence.

  • The buyer must generally be the first person to occupy the home after construction or substantial renovation is completed.

The timing rules differ slightly for owner-built homes, homes on leased land and co-operative housing. Buyers in those situations should review the applicable CRA requirements carefully.

Bill C-4 received Royal Assent on March 12, 2026, formally creating the new rebate.

Can the Builder Credit the Rebate at Closing?

Yes. A builder may agree to credit the rebate against the amount you owe at closing.

If the builder provides the credit, the builder must submit the rebate application to the CRA. The buyer cannot submit another application for the same rebate unless the builder provided only the existing New Housing Rebate and not the new First-Time Home Buyers’ rebate.

The builder may ask you to sign documents assigning the rebate to them. Read those documents carefully and confirm what happens if the CRA later determines that you do not qualify.

What If the Builder Doesn’t Credit the Rebate?

If the builder does not pay or credit the rebate, an eligible buyer can apply directly through their CRA account or submit the required application by mail.

For a home and land purchased from a builder, the main application is Form GST190: GST/HST New Housing Rebate Application for Houses Purchased from a Builder.

The application deadline is generally two years from the date ownership transfers to the buyer. Different filing requirements may apply when the buyer leases the land or builds the home.

Questions to Ask Before Signing a Builder Contract

Before relying on the rebate as part of your purchase budget, ask the builder:

  • Does the advertised price include GST?

  • Has any GST rebate already been deducted from the advertised price?

  • Will the builder credit both applicable rebates at closing?

  • Who will prepare and submit Form GST190?

  • Does the agreement require me to assign the rebate to the builder?

  • Who becomes responsible if the CRA later decides that I am ineligible?

  • Is the rebate shown clearly on the purchase contract and statement of adjustments?

These questions should be answered before the builder agreement becomes firm, not shortly before possession.

Get my free New-Construction Buyer Checklist

Want the GST questions above, plus everything else to check before you sign with a builder, in one place? My free, printable 2-page checklist takes you from your first show home visit to your one-year warranty.

Get the free checklist →

Frequently Asked Questions

Is the new-home GST rebate automatic?

No. The buyer must meet all eligibility requirements, and the required application must be submitted either by the builder or directly by the buyer.

Does the rebate apply to resale homes?

Generally, no. This rebate applies to qualifying newly built or substantially renovated homes and certain other eligible new-housing arrangements.

Can I qualify if my spouse previously owned a home?

Possibly, but the occupancy history matters. You generally cannot have lived in a home owned by you or your spouse or common-law partner during the current calendar year or the previous four calendar years. Confirm your circumstances with the CRA.

What happens if the home costs more than $1 million?

The rebate is gradually reduced between $1 million and $1.5 million. No First-Time Home Buyers’ rebate is available when the home is valued at $1.5 million or more.

Can I apply after taking possession?

Yes, when the builder has not credited the rebate and you otherwise qualify. The deadline for a typical home-and-land purchase from a builder is generally two years from the date ownership transferred to you.

Buying a New-Construction Home in the Edmonton Area?

The rebate can materially affect your purchasing budget, but it is only one part of a builder transaction.Financing can also affect affordability. If you're comparing 25- and 30-year amortizations, see my [2026 guide to 30-year mortgages in Alberta].

Before signing, buyers should also understand the specifications, upgrade pricing, deposit schedule, construction timeline, inspection rights, closing adjustments and what happens if the completed home differs from the plans.

With more than 25 years in new construction, on the trades and sales sides, I help buyers evaluate these details when purchasing new homes in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove and Stony Plain.

If you're comparing your options or planning a move in Edmonton, Sherwood Park, Fort Saskatchewan, Devon, Spruce Grove or Stony Plain, I can help you understand how the details fit into the bigger picture. With more than 25 years in new construction, on the trades and sales sides, I bring a builder’s-eye perspective to the buying process.

Call or text Jay Lewis at 780-220-8449

Jay Lewis | REALTOR® | RE/MAX Excellence

Want to see more Edmonton real-estate updates from JaySells.ca in Google? Add JaySells.ca as a Preferred Source.
This article provides general information only and is not tax, accounting or legal advice. Rebate rules are technical and can change. Confirm your eligibility and rebate amount with the Canada Revenue Agency, a qualified accountant and a real-estate lawyer.

Official Sources

Information reviewed and updated September 23, 2026.

Read
Data last updated on October 30, 2026 at 11:30 AM (UTC).
Copyright 2026 by the REALTORS® Association of Edmonton. All Rights Reserved.
Data is deemed reliable but is not guaranteed accurate by the REALTORS® Association of Edmonton.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by CREA and identify the quality of services provided by real estate professionals who are members of CREA.
Text Jay